Mobile operators across Asia Pacific are being asked to carry more AI-driven traffic while improving network economics, energy efficiency and spectrum utilization. That is pushing artificial intelligence deeper into radio access network architecture rather than limiting it to isolated optimization features.
Nokia has been expanding its AI-RAN work across the region, including deployments and trials that combine accelerated computing with radio infrastructure. TNGlobal previously covered Nokia, Indosat and NVIDIA’s AI-ready 5G deployment in Indonesia.
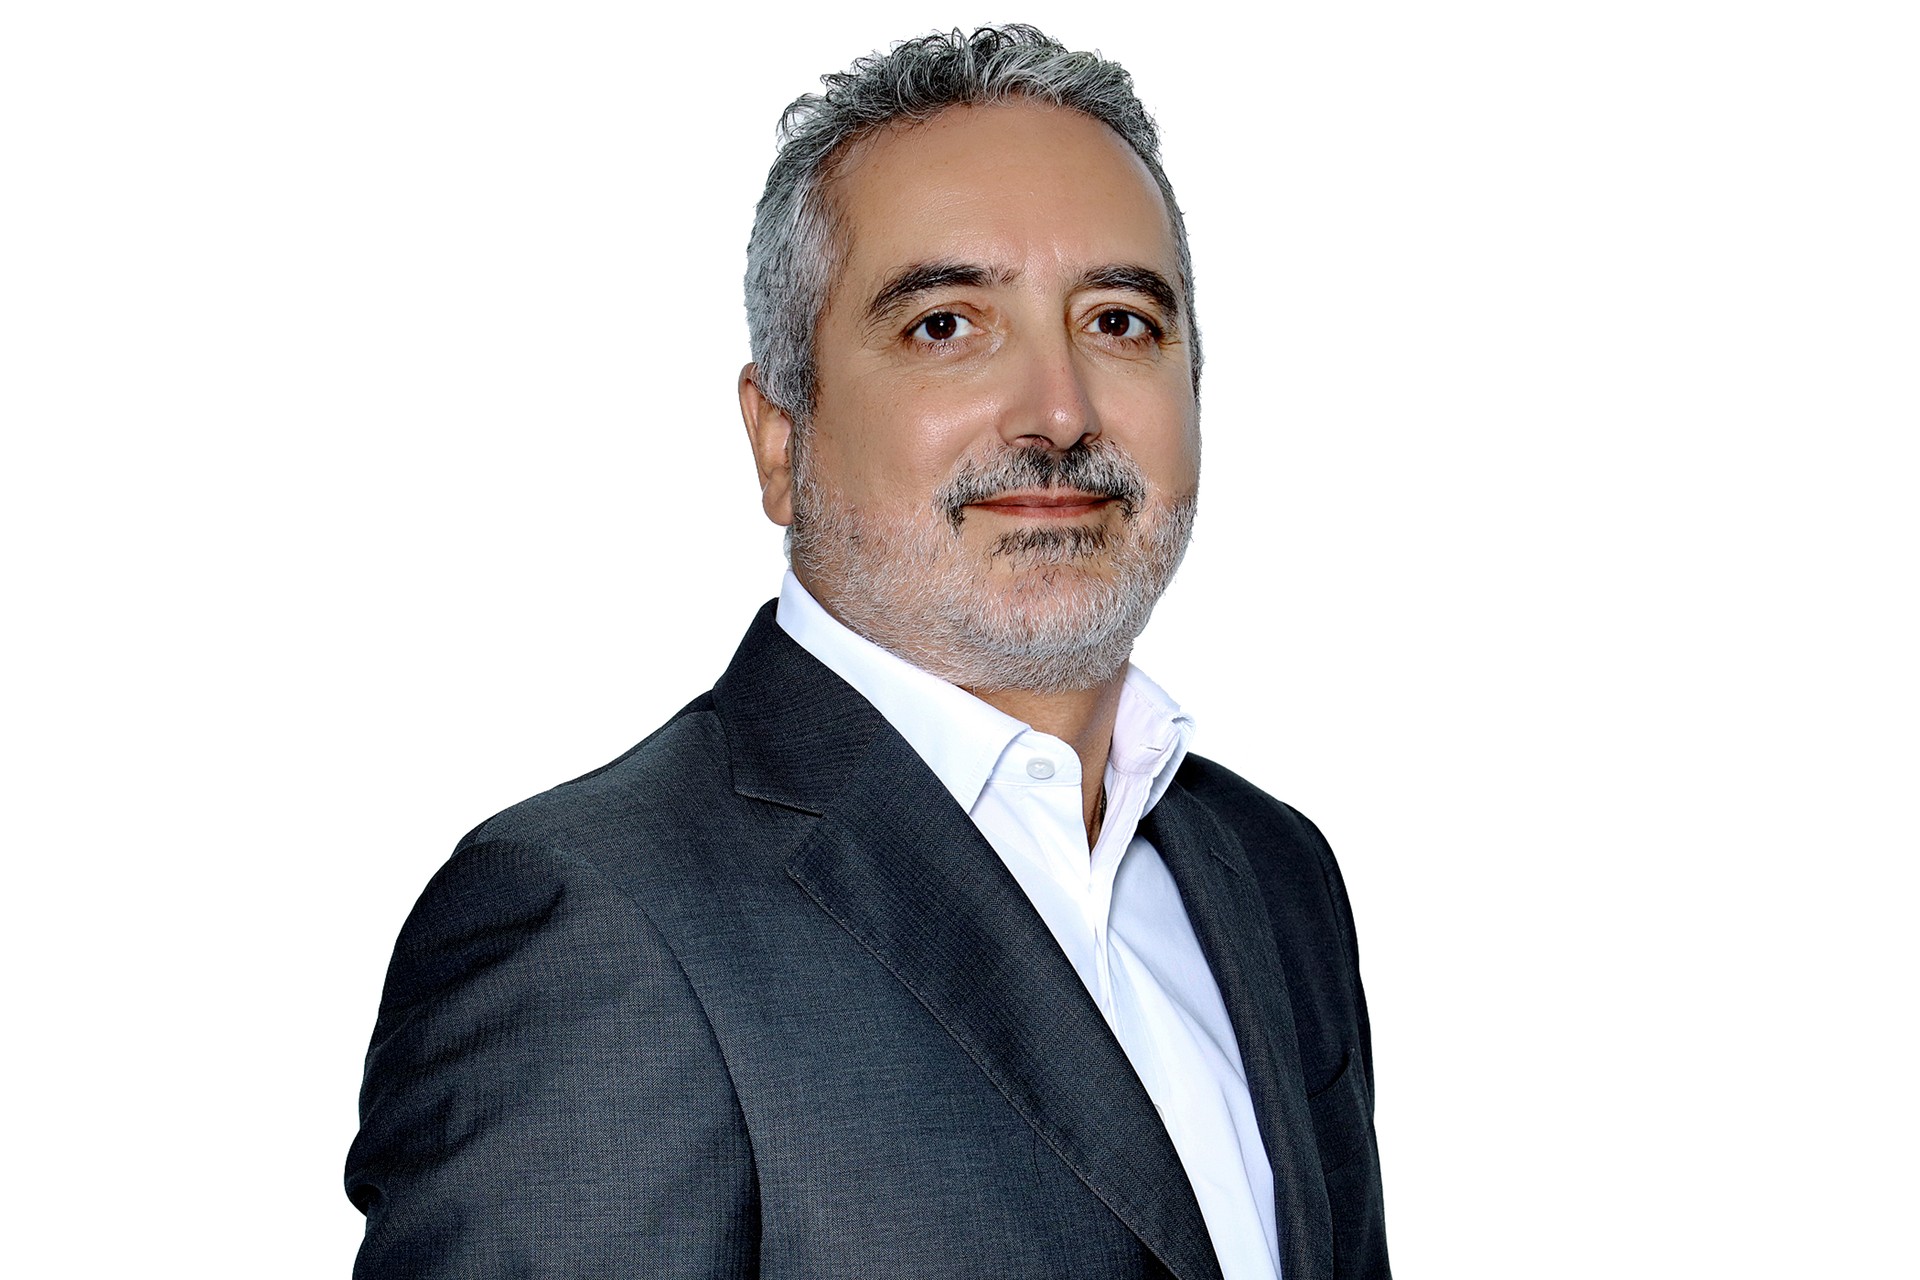
In this TNGlobal Q&A, Henrique Vale, Vice President of the Mobile Infrastructure Segment, Global Sales and Customer Operations, Asia Pacific at Nokia, discusses what changes when RAN becomes AI-native, how operators can evolve existing infrastructure, where measurable gains are emerging, and how governance and multi-vendor interoperability fit into the path toward 6G.
AI-native RAN can mean different things depending on how AI is incorporated into the network. At the architecture and operations level, what changes when a RAN is AI-native compared with a conventional RAN that has AI features layered on top?
The difference is that intelligence is built into the architecture and operating model, rather than added to individual functions afterward. An AI-native RAN combines AI-accelerated computing with software that can run real-time inference at radio timescales, continuously improving beamforming, channel estimation, interference management and traffic prediction.
It also separates innovation from traditional hardware cycles: new models, features and performance gains can be delivered through software. That makes the RAN an open, programmable platform that can support both AI for the network and AI applications beyond connectivity, while providing a practical evolution path from 5G and 5G-Advanced to AI-native 6G.
Nokia has described three deployment paths for AI-RAN. What are those paths, and how much of an operator’s existing radio, baseband, transport and software infrastructure can realistically be retained as it moves toward each model?
The principle is straightforward: three deployment paths, one AI-RAN platform and one shared roadmap to 6G. Operators can add an AI-accelerated plug-in card to an existing Nokia AirScale baseband; deploy an accelerated AI-RAN node alongside AirScale as a single logical base station; or take a cloud-native path using GPU-powered commercial off-the-shelf servers.
All three run on the same anyRAN software foundation. Existing radio and spectrum investments carry forward, while the amount of baseband and transport retained depends on the chosen architecture. This allows operators to modernize at their own pace without a wholesale replacement of their existing radio infrastructure.
What measurable improvements can operators reasonably expect from AI-RAN today in areas such as spectrum utilization, capacity, energy efficiency, network quality or operating costs? Which gains are highly dependent on traffic patterns, available spectrum or hardware configuration?
The immediate opportunity is to get more capacity and better performance from the spectrum and infrastructure operators already own. Nokia’s AI-driven radio innovations have already demonstrated more than 20 percent spectral-efficiency gains, with a roadmap targeting approximately 50 percent by 2027 and more than 100 percent by 2028.
The platform is designed to increase busy-hour and uplink performance within a comparable power and hardware envelope, improving customer experience and reducing cost per bit. These are roadmap targets rather than uniform outcomes: realized gains will vary with radio-channel conditions, mobility, cell-edge performance, traffic patterns, spectrum configuration, fronthaul architecture and the hardware deployed.
AI-native networks also introduce additional accelerated computing and real-time inference requirements. How should operators evaluate the added capital, power and operational costs against the network efficiencies AI-RAN is intended to create?
Operators should evaluate the economics over the life of the network, rather than treat accelerated computing as an isolated cost line. The right comparison is the incremental capital and power required against the value of additional capacity from existing spectrum, deferred cell splitting and hardware refreshes, continuous software-driven performance gains, lower energy and cost per bit, and higher utilization where RAN and AI workloads share compute.
The business case will also vary by deployment path. Adding acceleration to an existing AirScale site has a different cost profile from deploying a standalone node or a greenfield cloud-native architecture. The question is not simply what the compute costs, but what capacity, flexibility and infrastructure longevity it unlocks.
There is growing interest in using distributed RAN infrastructure as an edge-compute layer for AI inference. Which use cases do you think are technically and commercially realistic over the next two to three years, and which remain more experimental?
We see three related opportunities. AI for RAN uses AI to improve radio performance, energy efficiency and operations. AI and RAN allows radio and AI workloads to share accelerated computing, raising utilization and improving the return on that infrastructure. AI on RAN uses the network’s connectivity, data and programmability to support AI applications.
Over the next two to three years, the strongest commercial potential is inference that needs low latency, data locality or predictable performance, including industrial automation, video analytics, immersive applications and early physical AI use cases. Large-scale distributed training and highly dynamic multi-tenant inference remain more experimental and will require more mature orchestration, security and commercial models before they scale broadly.
How does AI-RAN fit into multi-vendor and Open RAN environments? As operators introduce AI models, accelerators and new software layers, how can they avoid replacing one form of vendor lock-in with another?
Openness is essential because AI-RAN should expand customer choice, not narrow it. Nokia’s platform is designed for 5G and 5G-Advanced, with full O-RAN compliance and a software upgrade path to 6G. Its common anyRAN software can run across different hardware architectures and supports open interfaces, APIs and multi-vendor ecosystems.
Operators should look for portability across silicon, model formats, APIs and orchestration, together with transparent model-lifecycle tooling. An open ecosystem of radio, silicon, cloud and software partners allows each layer to innovate independently while preserving interoperability, investment protection and competition.
Once AI systems begin influencing radio optimization and other network behavior, what security, model-lifecycle and governance controls become necessary? Where should operators retain human oversight, override capability and auditability?
The objective is innovation with control. AI models influencing live network behavior should be observable, tested, auditable and reversible. Operators need rigorous model versioning, validation before deployment, continuous monitoring for drift or anomalous behavior, and protection for models, data and software supply chains.
They should retain real-time override and rollback capability, with clear records of what a model changed, why it acted and whether the outcome remained within operator-defined intent. Human oversight should be strongest where decisions affect service assurance, safety, regulation or customer commitments. AI should operate as a glass box, not a black box.
APAC includes both mature 5G markets and markets still managing major coverage and investment constraints. Where do you expect commercial AI-RAN adoption to emerge first in the region, and how will the business case differ across those operator environments?
We expect the strongest early conditions in APAC where operators face dense traffic, constrained spectrum, advanced 5G footprints and pressure to improve network economics. In those environments, the near-term business case is more capacity from existing spectrum, better uplink and busy-hour performance, and a lower cost per bit.
In markets still prioritizing coverage and capital discipline, the case will be different: operators can choose a deployment path that fits their investment cycle, introduce AI acceleration where it creates value and preserve a software-led route to more advanced capabilities. Adoption will therefore be driven less by geography alone than by traffic demand, spectrum economics, infrastructure maturity and readiness to adopt new operating models.
Henrique Vale is Vice President of the Mobile Infrastructure Segment, Global Sales and Customer Operations, Asia Pacific at Nokia. He leads Nokia’s Mobile Infrastructure business segment across the region and has more than 20 years of international experience across research and development, operations, consultancy and sales.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Nokia, Indosat, NVIDIA to deploy AI-ready 5G network across Indonesia