AI data-center expansion is increasing competition for power, grid connections and suitable sites that Bitcoin miners have historically used. That is forcing mining operators to compare the value of a megawatt deployed to hashing with the potential economics of AI or high-performance computing.
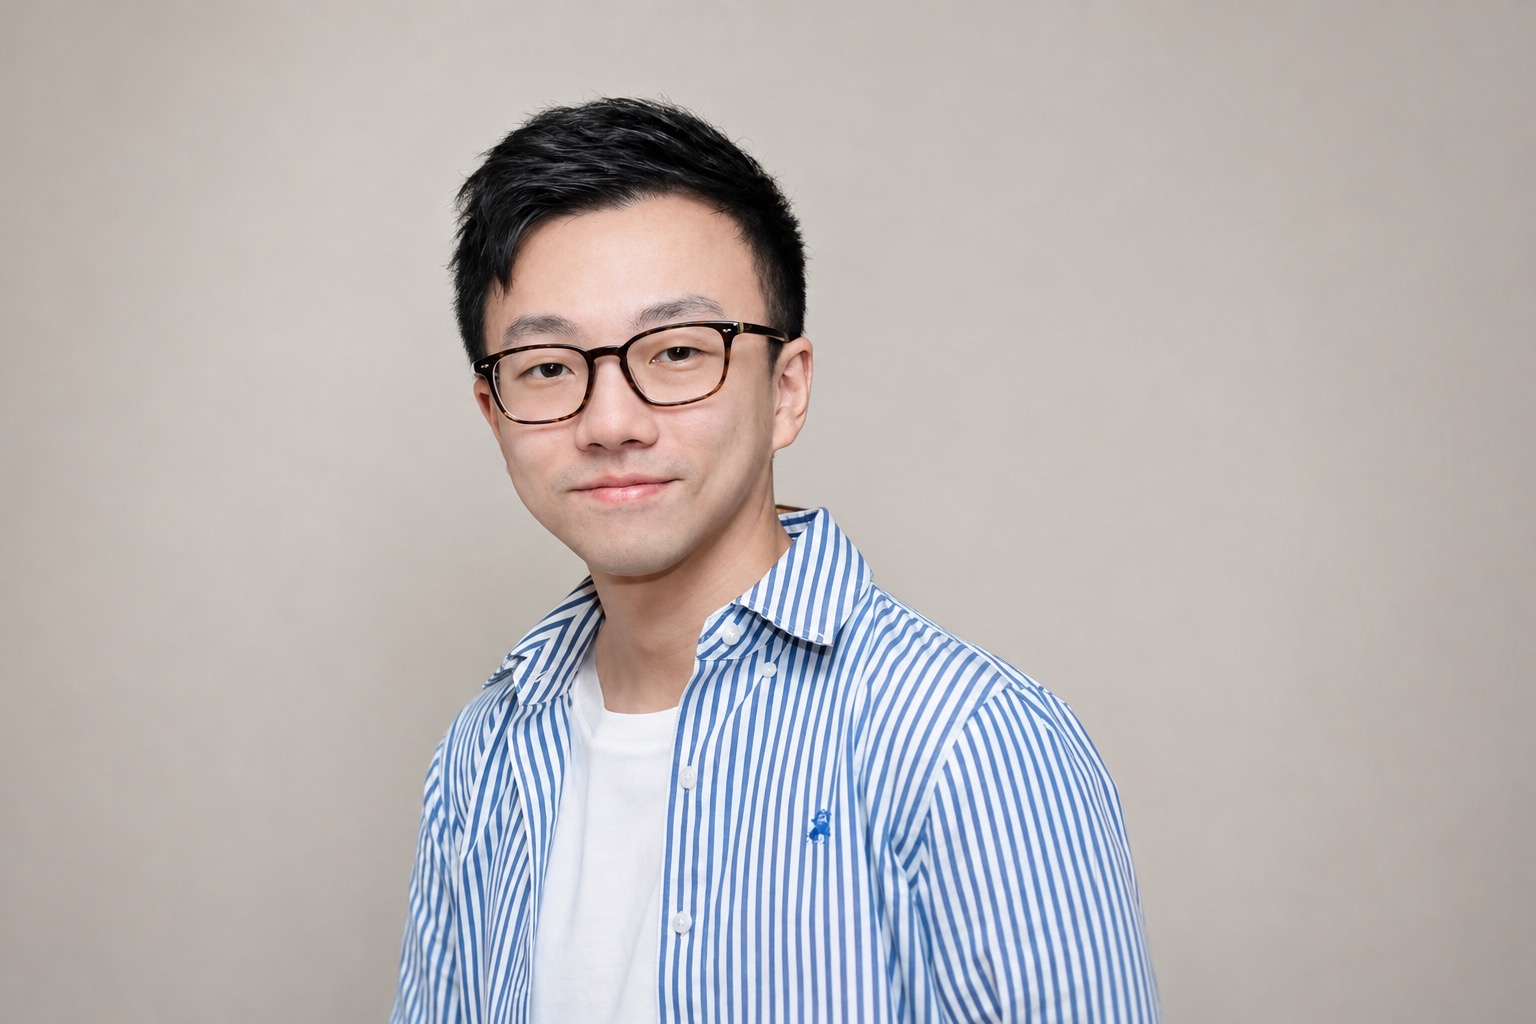
In this TNGlobal Q&A, Jeff Ko, Chief Analyst at ViaBTC, discusses how AI infrastructure demand is changing mining-site economics, which assets can be reused for AI/HPC, where miners still have an advantage as flexible loads, and what would make the convergence between mining and AI infrastructure a lasting structural shift.
AI data centers and crypto miners are increasingly competing for power, sites and grid capacity. What changes are you seeing in the economics of Bitcoin mining as AI infrastructure demand accelerates?
AI is clearly raising the opportunity cost of power. For miners, the economics are no longer just about securing the lowest electricity price, but also whether the same power, land and grid connection could generate higher returns from AI or HPC. With that, miners increasingly need to think about the broader economics around hashrate, including financing, hedging, power costs and the alternative value of the site itself.
This is creating greater segmentation. Sites with strong grid access, fiber and high uptime are increasingly valued as data-center assets, while Bitcoin mining is shifting toward cheaper, more remote, intermittent or interruptible power.
That said, mining still has a structural advantage: flexibility. AI data centers generally require highly reliable power, whereas miners can operate closer to stranded or curtailed energy and reduce consumption quickly when the grid is under stress.
In short, I don’t think AI will simply displace Bitcoin mining. It is forcing miners to be much more disciplined about where each megawatt is best deployed.
Which parts of a mining site can realistically be repurposed for AI or HPC workloads, and which parts usually require substantial redesign or replacement?
A useful rule of thumb is that much of what sits upstream of the main transformer can be reused, while much of what sits downstream needs to be rebuilt. The most valuable part of a mining site is often its grid connection, including the utility agreement, substation, interconnection position, land and permits. In many markets, a large-load connection can take years to secure, so an already energized site has significant value for AI or HPC operators.
What generally cannot be reused directly is the compute layer. ASIC miners have no practical use for AI workloads, and mining racks, containers and basic air-cooling systems are typically not designed for GPU clusters.
AI and HPC facilities also require higher standards for fiber connectivity, cooling, redundancy and uptime, often including liquid cooling, UPS systems and backup generation. So converting a mining site is rarely as simple as swapping ASICs for GPUs. The transferable value is mainly the power access and land, while the data-center layer still requires substantial redesign and capital investment.
For miners deciding whether to keep deploying capital into Bitcoin mining or diversify into AI/HPC, which financial and operating metrics matter most today?
The key question is not simply which business generates higher revenue, but which offers the better risk-adjusted return per megawatt and per dollar of capital invested.
For Bitcoin mining, the core metrics remain hashprice, machine efficiency, all-in power cost, uptime and ASIC payback periods. Miners also need to stress-test returns against Bitcoin price, network difficulty and future halvings, as mining economics can change quickly.
For AI/HPC, the focus shifts toward capex per megawatt, utilization rates, power reliability, cooling and network requirements, financing costs, and the quality and duration of customer contracts. AI may generate higher revenue per megawatt, but it also requires significantly more upfront capital and typically involves longer development timelines.
Are long-term power contracts becoming a more important strategic asset as AI operators compete for the same energy supply? How is this affecting site selection and expansion decisions?
What has become truly strategic is deliverable capacity at a specific location and on a specific timeline. A long-term power contract does not necessarily have the same value for a miner as it does for an AI operator. For an AI operator with a 10- to 15-year tenant lease, a long fixed-price contract can be a natural hedge. For miners, the more important terms are often flexibility rights rather than headline price, including the ability to curtail, resell power during price spikes or assign the contract to a third party.
Prime grid-connected sites in mature markets are increasingly being absorbed by AI demand. That is pushing miners toward locations where AI is less able to compete, such as sites near power plants, stranded gas, curtailed renewables or state utilities with surplus capacity, including parts of Africa, Latin America, Central Asia and the Middle East.
These regions bring a different set of risks, so expansion is also becoming more modular and geographically diversified rather than concentrated in a small number of large sites.
Where can AI itself improve mining operations, for example in power management, cooling, predictive maintenance, fleet optimization or security, and where is the impact currently overstated?
The clearest opportunity is in operational optimization. Mining sites generate large amounts of real-time data on power consumption, machine temperature, hashrate, fan performance and failure rates, while operators are constantly balancing power prices, hashprice and machine condition. With margins often thin, even a few percentage points of improvement in energy use or uptime can materially affect profitability. In practice, much of the value comes from better forecasting combined with traditional optimization.
Security is equally important. At the pool level, behavioral models can help detect account takeovers, suspicious changes to payout addresses, malicious firmware that redirects hashrate and attacks on pool infrastructure.
Cooling is one area where the impact is sometimes overstated. Well-run mining sites, particularly immersion-cooled, hydro-cooled or cold-climate air-cooled operations, already consume relatively little energy beyond the mining machines themselves. There may simply be less left to optimize than the headline claims imply.
Could competition from AI data centers push more mining activity toward new regions or markets? What would that mean for the geographic distribution and resilience of Bitcoin mining?
As grids develop and higher-value users emerge, whether AI, industry or growing household demand, mining tends to be displaced and move to the next frontier. We have seen this cycle before: mining first concentrated in China’s hydro-rich provinces, then shifted toward markets such as Texas and the Nordics. Today, AI is increasingly competing for the best grid-connected sites in North America.
The difference this time is that the shift is gradual and market-driven rather than triggered by a sudden regulatory ban. That should make the transition more orderly than the 2021 migration out of China.
Competition from AI could push more mining toward regions with abundant power that is less suitable for traditional data centers, including stranded hydro, curtailed renewables, excess generation or areas with weaker fiber connectivity. We are also seeing more state-led energy monetization across parts of Africa, Central Asia, the Middle East and South Asia.
Cheap power alone is not enough. Miners still need regulatory stability, grid reliability, logistics and access to capital. I expect geographic diversification to improve Bitcoin’s resilience, but the industry will need to balance lower-cost power against higher political, operational and infrastructure risks.
Bitcoin miners have often argued that they can act as flexible loads for power grids. How does that compare with the operating requirements of AI data centers, which may need more continuous power availability?
This is one of the clearest structural differences between Bitcoin mining and AI infrastructure. Bitcoin mining is highly interruptible: machines can reduce load or shut down quickly when power prices spike or the grid is under stress, then resume when conditions normalize.
AI data centers generally require much more continuous and reliable power because workloads, customers and service-level agreements depend on uptime. That means they typically need stronger redundancy, backup systems and more stable grid capacity.
For power systems, this makes mining potentially complementary to AI rather than directly comparable. Miners can absorb excess generation during low-demand periods and curtail when electricity becomes scarce, which can help balance variable renewable supply.
Technical flexibility is not the same as economic willingness to curtail. Miners still need to weigh the value of shutting down against the mining revenue they give up. So while mining is structurally better suited to flexible and interruptible power demand, the decision ultimately remains an economic one.
Over the next 12 to 24 months, what would convince you that the convergence between crypto mining and AI infrastructure is a lasting structural shift rather than a temporary response to current AI demand?
I would first look at what comes after the initial wave of deals, such as renewals, capacity expansions and new long-term leases with investment-grade tenants. That would show that demand is durable rather than simply driven by the current AI investment cycle.
The second test is what happens when AI capex eventually slows. If miner-hosted AI contracts remain intact without widespread renegotiation, cancellations or tenant defaults, then the shift is likely structural. If those sites simply revert to Bitcoin mining, it was probably more cyclical.
Jeff Ko is Chief Analyst at ViaBTC. He previously worked at J.P. Morgan Private Bank and founded data-visualization startup Chartipedia in Finland before entering the crypto industry.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
AI is turning old crypto code into a new attack surface, says CoinEx chief analyst Jeff Ko [Q&A]