Singapore has continued to attract semiconductor investment, but the next stage of value creation increasingly depends on what happens inside existing factories: equipment integration, data quality, cybersecurity, engineering productivity and the ability to move AI from pilots into production.
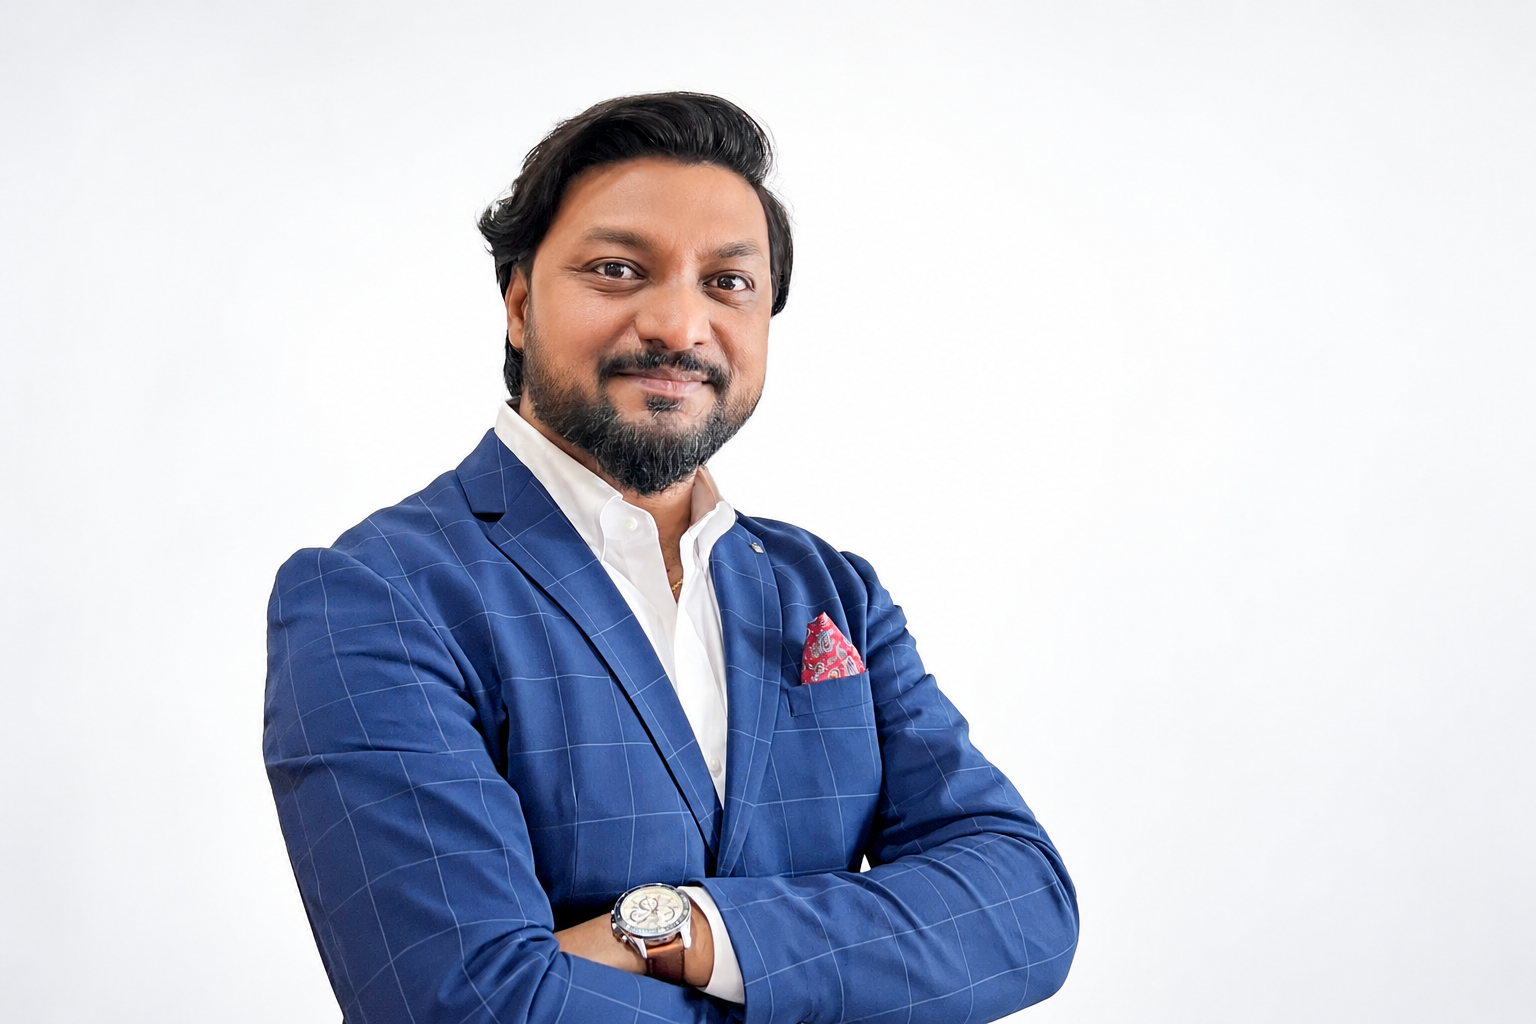
TNGlobal spoke by email with Rohan Chowdhary, Head of Digital & AI Innovation, Southeast Asia, at UST, about brownfield modernization, factory-floor AI, the Singapore-Malaysia semiconductor corridor and the capabilities needed to move further up the value chain.
From the factory floor, what is now the biggest constraint on capturing more value, equipment integration, process know-how, software, data, talent, or something else?
Singapore has pulled in more than S$30 billion in semiconductor investment over the past four years, with a further S$800 million committed to semiconductor research under the RIE2030 program, per the Singapore Economic Development Board. The constraint has moved from winning the next fab to how much value each dollar of installed capacity produces once running.
That makes productivity, rather than capacity, a bigger constraint. Singapore has built a strong position in advanced manufacturing because it is trusted for precision, reliability and process discipline, but the next source of value will come from how intelligently manufacturers operate the assets already in place. On the factory floor, that means better integration between equipment, MES, production systems and engineering workflows, so that data can move quickly enough to improve yield, reduce cycle time and support faster decision-making. Talent remains critical, but the hardest capability to build is increasingly the combination of process engineering, software, data and operational know-how in one operating model.
This is also where the Singapore-Malaysia corridor becomes relevant. Malaysia, particularly Penang, brings deep strength in assembly, testing, packaging and electronics manufacturing, while Singapore is positioned around higher-value manufacturing, R&D and production control. From UST’s perspective, having operated in Malaysia since 2006 and built capabilities through its Penang delivery center and Infinity Lab, the opportunity is to help manufacturers connect these parts of the value chain more effectively. In practice, the constraint is less about whether the region has machines, engineers or data, and more about whether those assets can work together well enough to lift productivity and capture more value from each stage of semiconductor production.
Where do digitalisation projects usually become difficult in brownfield fabs and electronics plants, when connecting machines, MES, production systems and operational data?
Most semiconductor and electronics plants in this region were not built as one system. They were built machine by machine, vendor by vendor, over ten, fifteen, twenty years. The hardest part is rarely the newest equipment. It is the layer in between, older PLCs, proprietary protocols and point solutions never designed to share data with an MES or an ERP. The real challenge is not connecting machines, but making their data usable across MES, production and business systems.
Friction usually shows up in three places, physical connectivity between machines, a data model reconciling information from different sources, and the change management needed to build operator trust in a new layer of visibility. In our experience, programs work better when they start with a specific line or tool class and a measurable production problem, rather than the entire site at once. Manufacturers succeed when they treat digitalisation as a phased engineering program tied to specific outcomes, not a single big platform switch.
This is where UST’s work with brownfield manufacturing environments is relevant. In many fab and electronics plants, the practical challenge is not to replace legacy assets, but to connect them safely and incrementally so they can become part of a more intelligent production environment. That often means building the integration layer around existing machines, harmonizing data from fragmented systems, and giving engineers and operators a clearer view of how equipment, process parameters and production outcomes relate to one another. The goal is not a big-bang transformation, but a connected-machine architecture that allows plants to modernise without disrupting production.
Where are you seeing measurable value from AI and analytics today, and where are manufacturers still running pilots without enough operational impact to justify wider deployment?
Globally, the picture is sobering. McKinsey’s research highlights that only about two percent of manufacturers describe AI as fully embedded across their operations, and roughly two out of three remain in exploration or targeted pilots. Nearly sixty percent lack clear AI targets, and those that set them tend to hit or beat them more often. Governance is often what determines whether a pilot scales, not simply the model itself.
Measurable value tends to concentrate in narrow, well-instrumented processes with a tight feedback loop between machine output and engineer action. Predictive maintenance on a single tool class, or tighter process control on one line, holds up under scrutiny, with fewer stoppages and steadier yield on that step. Plant-wide yield programs are where pilots most often stall, layered onto a facility before the data and process are ready.
Semiconductor validation is a useful test case for where the industry needs to head, pairing AI reasoning with the engineering context of one process rather than a general model layered over the whole plant. Applied that way, cycle times can fall fifty to seventy percent, compressing a four-day turnaround into about forty-eight hours, the clearest sign yet of what disciplined AI deployment inside one process can do. UST has recorded that result since bringing Claude into its iDEC validation platform, under its enterprise-wide partnership with Anthropic.
More data does not necessarily mean better decisions. What data-quality or contextualization problems most often limit AI use on the factory floor?
Semiconductor plants generate enormous volumes of data, from machines and process data to sensor readings, tool logs, and test results. However, volume has never been the constraint. Understanding the context behind all the data is the problem.
A reading from a tool means very little on its own. What matters is which lot, which recipe, which chamber condition and which operator action sat behind it, and in many plants that context lives across systems never designed to talk to each other.
Engineers need to trust the data before they trust a model built on it, and legacy equipment with thin telemetry or manual entry undermines that trust. In a factory environment, poor data quality is not just an efficiency problem. If an AI model is trained on incomplete, mislabelled or poorly contextualized data, it can recommend the wrong maintenance action, miss an early warning signal or create false confidence around a process that should be escalated. That has implications for productivity and yield, but also for equipment safety, worker safety and the integrity of production decisions. A short data audit, mapping what is captured against what a decision genuinely needs, usually surfaces more value than new sensors. The stronger approach is to contextualise, clean and govern data before scaling the AI layer.
As IT and OT become harder to separate, how should manufacturers expand visibility and data access without increasing cybersecurity risk or disrupting production?
As factories connect more equipment, software and data, the line between information technology and operational technology keeps blurring, and that boundary is where attackers now look. Our CyberProof threat intelligence shows identity, cloud and software as a service environment account for roughly twenty-two percent of all incidents, and about twenty-two percent of confirmed breaches start with stolen or compromised credentials.
Vulnerability exploitation is up seventeen percent year on year, with ERP systems, collaboration platforms and identity services among the most targeted. A proven starting point is segmenting the network into clearly defined zones, keeping production controllers isolated from corporate systems while still allowing data out for analysis, then expanding visibility from the edges inward rather than opening core production control systems directly.
The risk also expands as manufacturing becomes more tightly connected to business operations. Production data increasingly needs to flow into demand planning, procurement, warehouse management, quality, fulfilment and logistics systems so manufacturers can make faster decisions across the value chain. That creates real operational value, but it also widens the attack surface because a compromise in identity, ERP, supplier portals or planning tools can have consequences for plant performance and fulfilment, not just office systems. The security model therefore has to cover both directions of the connection, including protecting production assets from enterprise-side risk, while ensuring operational data can still move securely to the business processes that depend on it.
Manufacturers do not need to choose between visibility and safety. A modern security operations model, built on continuous monitoring and managed detection and response, lets teams see what is happening without disturbing tightly controlled production.
Which capabilities are hardest to build locally now, and what mix of reskilling, specialised hiring and automation will be needed over the next few years?
Singapore’s own numbers tell the story. The Ministry of Manpower added semiconductor engineers, instrumentation engineers and process engineers to its Shortage Occupation List in November 2024, acknowledging that demand is outpacing supply. Singapore Institute of Technology’s engineering intake grew nearly nineteen percent between 2022 and 2024, and companies including Micron and GlobalFoundries have built internship and scholarship pathways with the polytechnics and ITE.
The harder capability to build locally is the cross-disciplinary profile, engineers who understand both the physical process and the software and data layer above it, a smaller pool everywhere. Across Southeast Asia, the most valuable roles will sit between process engineering, automation, data science, cybersecurity, cloud and manufacturing operations, because factories increasingly need people who can connect equipment decisions to production, quality, planning and supply-chain outcomes.
The right mix for the region puts reskilling first, specialised hiring for the harder gaps and automation absorbing repetitive work, so scarce engineering talent can focus on higher-value judgement and problem-solving.
UST approaches this in the same way inside its own workforce and with clients. Through UST Step IT Up, the company builds customised upskilling and reskilling pathways, including apprenticeships and practical training in areas such as AI, cloud, data analytics, cybersecurity, legacy systems and role-specific technical skills.
More recently, UST also committed to training 20,000 employees globally on Claude as part of its strategic alliance with Anthropic, including engineers, architects and consultants working across physical AI, semiconductor validation, manufacturing and connected systems. For Southeast Asia, that kind of model matters because the talent answer cannot depend only on hiring ready-made specialists. It has to combine graduate pipelines, mid-career reskilling and applied, project-based learning close to the factory floor.
How does Singapore compare with Taiwan, South Korea and Malaysia in factory digitalisation? Where is the genuine advantage, and where are other markets moving faster?
Having worked across Southeast Asia, I see each market advancing digitalisation from a different position. Taiwan and South Korea benefit from decades of ecosystem development, deep supplier networks, and highly automated manufacturing environments. Their advantage is scale, ecosystem depth, and operational maturity.
Singapore’s strength lies elsewhere. It combines advanced manufacturing, R&D, strong IP protection, and a trusted business environment. Its real advantage is the ability to translate innovation into production outcomes quickly and consistently. The focus is no longer just on adding capacity, but on improving productivity, resilience, and operational intelligence.
Malaysia, particularly Penang, continues to strengthen its position in assembly, test, packaging, and electronics manufacturing while accelerating investments in automation, smart manufacturing, and advanced packaging capabilities.
The bigger opportunity is not competition, but complementarity. Together, Singapore and Malaysia form a highly integrated semiconductor corridor spanning wafer fabrication, advanced packaging, assembly, testing, R&D, and manufacturing operations. While other markets may move faster on fabrication scale, Singapore has an opportunity to lead in factory-floor intelligence, AI-enabled operations, and cross-border digital integration. The ability to connect data, production, and talent seamlessly across the value chain could become one of Southeast Asia’s strongest competitive advantages.
Looking three to five years ahead, which operational or capability metrics would convince you Singapore has moved further up the semiconductor value chain, rather than simply counting new investment announcements?
Looking ahead, I would focus less on new investment announcements and more on the outcomes they create. Capital investment matters, but the real measure of progress is how effectively manufacturers convert technology, talent, and existing capacity into higher productivity, better yields, and greater innovation.
Four metrics stand out.
First, cycle-time and decision-speed improvements. If AI and advanced analytics can significantly reduce engineering and validation turnaround times while maintaining quality, it shows digitalisation is delivering measurable value.
Second, R&D-to-production conversion. Success should be measured by how quickly innovations in areas such as advanced packaging, photonics, and power semiconductors move from research into high-yield manufacturing.
Third, cross-disciplinary talent. Future factories will need engineers who can bridge process engineering, automation, software, data, cybersecurity, and AI. Developing this talent will be a key indicator of long-term competitiveness.
Finally, regional digital integration. The next phase of value creation will depend on how seamlessly Singapore and Malaysia operate as a connected ecosystem. Real-time visibility, shared data, and integrated decision-making across the supply chain will be critical differentiators.
Ultimately, if Singapore delivers faster engineering decisions, stronger yields, higher-value manufacturing activities, deeper digital integration, and a stronger pool of cross-disciplinary talent, it will have clearly moved further up the semiconductor value chain. The goal is not simply more capacity, but smarter and more intelligent manufacturing.
Rohan Chowdhary is Head of Digital & AI Innovation, Southeast Asia, at UST. He leads digital, AI and technology services across the region and UST’s Innovation Hub in Malaysia, with a focus on AI, intelligent automation, digital engineering, cloud, data and manufacturing transformation.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Asialink’s Patricia Poco-Palacios on scaling MSME lending with credit discipline [Q&A]