Asialink Group of Companies has been expanding its lending portfolio while keeping much of its exposure focused on micro, small and medium-sized enterprises. As that portfolio grows, underwriting thin-file borrowers, monitoring early signs of repayment stress and deciding where technology should support rather than replace human judgment become more important operating questions.
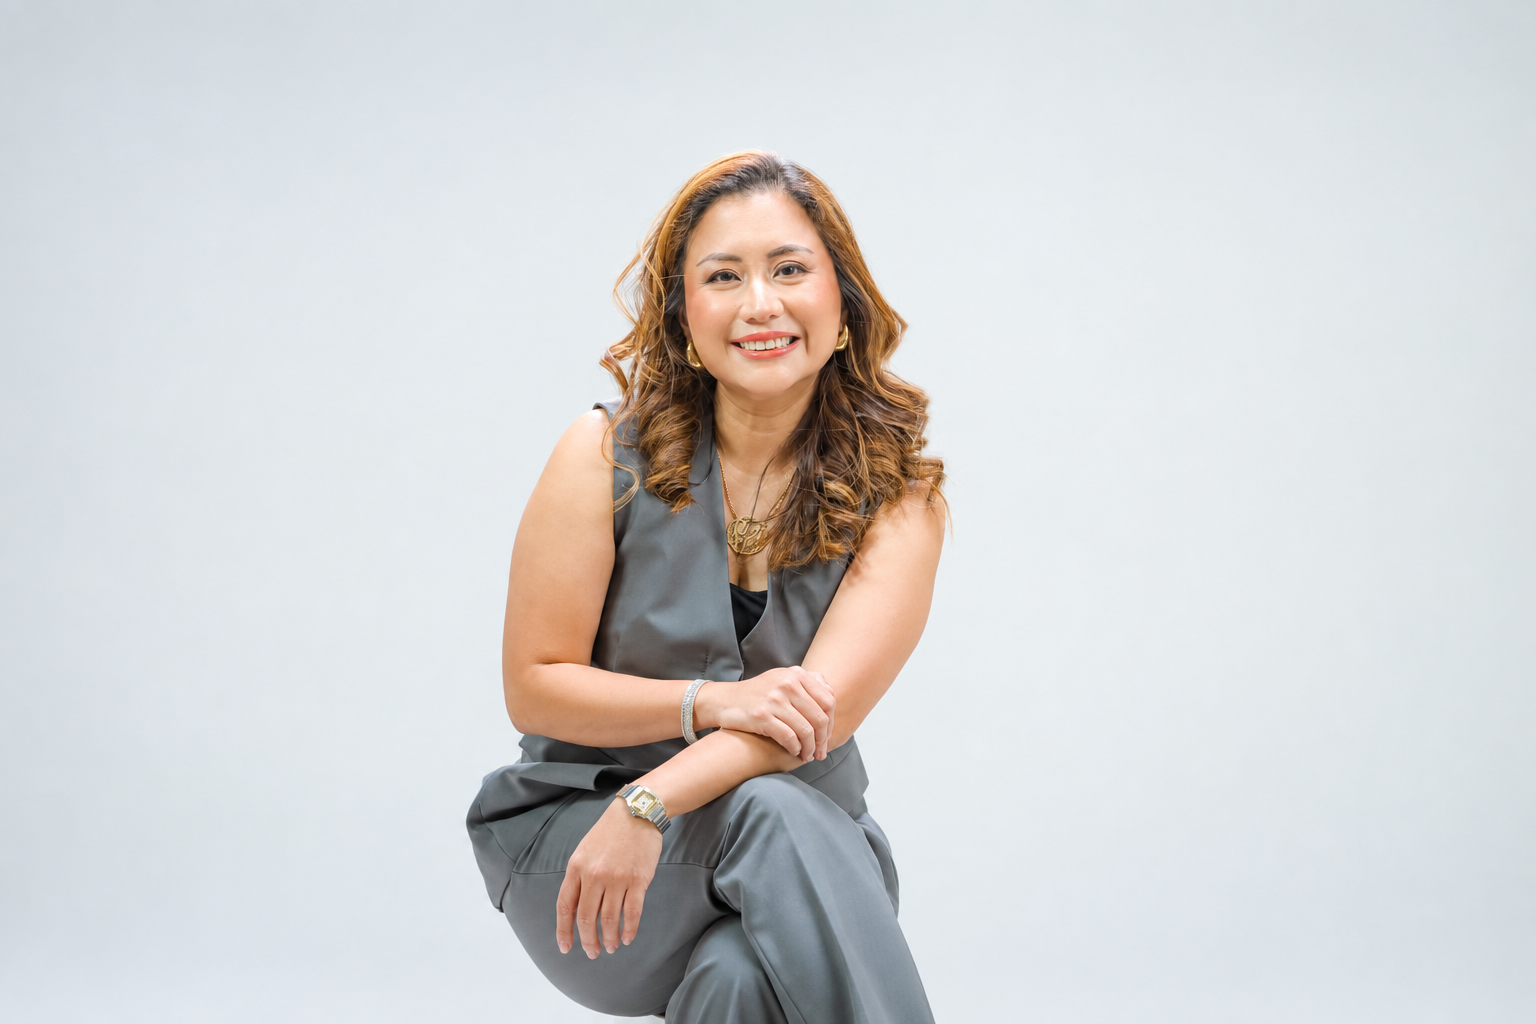
In this TNGlobal Q&A, Patricia Poco-Palacios, Group Deputy CEO of Asialink Group of Companies and a trustee of the Philippine Finance and Lending Association, discusses credit discipline, alternative signals for MSME lending, financial inclusion and the role of AI-assisted underwriting.
Asialink has reported PHP 50.2 billion in assets under management, with about 60 percent attributed to MSME borrowers.
Asialink says 60 percent of its PHP 50.2 billion in AUM comes from MSME borrowers, across more than 165,000 active clients. As the portfolio has grown, what has had to change most in underwriting and portfolio management to keep risk controls from lagging behind scale?
As we continue to scale, balancing the willingness to lend versus managing the risks warranted a more granular approach to guarding our portfolio quality. This meant tracking more indicators beyond the usual financial metrics, comparing and contrasting what’s working for one company versus what’s not working for another, and continually enforcing our decades-worth of lessons in maintaining our credit discipline. We expect AUM to grow further by the end of the year; I like to think that we’ve been sustainable in our growth trajectory because we make it a point to also ensure the success of the clients that borrow from us, not just ourselves.
Many small businesses remain thin-file borrowers. Which alternative data or non-traditional signals have proven most useful in assessing repayment capacity, and which signals do you think lenders should be cautious about over-relying on? Collateral-backed and vehicle financing can help reach borrowers who may not qualify for conventional bank credit. How do you make sure underwriting still focuses on the underlying business and cash flow rather than relying too heavily on collateral value?
Some MSMEs struggle to access affordable financing options because of not having documented records or not being incentivized to formalize their financial statements. For clients falling under that category, we do what we can to “reconstruct” and have a better understanding of their cash flow and repayment means. In some cases, that includes more meaningful conversations with the MSME owners themselves and visiting their businesses for us to get a better idea of their likelihood of growth. As much as we can, we want to be in a position where we are confident that a client availing our financing services will directly contribute to their business’ success and the local economy.
The Group reported a 2 percent non-performing loan ratio as of end-June 2026. What controls or early-warning indicators have been most important in maintaining portfolio quality, especially when borrowers face higher operating costs or uneven cash flow?
One key metric we take a look at is our “non-starters” bucket; it refers to clients that haven’t been able to make any payments on the loan. Our review cadence, and our quick decision-making on credit policy changes have served us for years. This discipline is the key not only for protecting our NPL ratio and other financial metrics, but to ensure we maintain pricing that’s considerate of our clients, especially given the economic climate.
Asialink has raised funding from banks and development-finance institutions. How does access to longer-term or sustainability-linked capital affect the pricing, tenor or structure of financing you can offer MSMEs?
Better pricing, better rates for borrowers. To be a homegrown group backed by international institutions with international credit ratings…we take it as a call to remain a responsible systems participant and properly represent NBFIs (non-bank financial institutions) towards a more precise and personalized financial inclusion as well as grassroots-driven economic development.
Some of Asialink’s recent facilities target rural MSMEs, women-owned businesses and other underserved segments. Beyond disbursement volume, what outcomes should lenders measure to determine whether this financing is actually improving access and business resilience?
Renewal rates provide good indication that a financing or lending company truly helped a client’s business.
From your perspective as a PFLA trustee, what industry-level gaps still make responsible non-bank lending harder in the Philippines? Are there changes in credit information, digital identity, regulation or borrower education that would make the biggest difference?
Beyond our industry, much has been said and done about elevating financial literacy; it remains a structural gap that multiple sectors, including us, are contributing in addressing through collaborations or through our own social impact initiatives.
Over the years, there’s been considerable effort from both the public and private sector to mainstream tangible concepts like responsible borrowing, financial consumer protection, understanding one’s credit score, and others. We at the PFLA remain supportive and will support initiatives that will endeavour to help underserved Filipinos become more fluent in navigating the financial ecosystem, and in some cases, enable them to have a more entrepreneurial spirit or mindset.
Looking ahead over the next two to three years, where do you expect technology, including AI-assisted underwriting and digital origination, to have the biggest impact on MSME finance? Which parts of lending should remain deliberately human-led?
Tech, including AI, will continue to primarily contribute in assisting firms in triangulating more data points to make better credit decisions, including risk-based or even towards a more “hyperpersonal” means of pricing. That being said, the Group’s “phygital” way of borrower engagement is primarily driven by our fleet of branch agents, loan consultants, and network of partners who take the time and effort in reaching out and knowing our clients. Being deliberate on the human front, I think, is the reason why we’ve stayed for so long.
Patricia Poco-Palacios is Group Deputy CEO of Asialink Group of Companies. She previously spent more than 20 years with Global Dominion Financing Inc., concluding her tenure there as President and CEO. She also serves as a trustee of the Philippine Finance and Lending Association, where she chairs the Ways and Means Committee. Poco-Palacios holds an MBA from the Ateneo Graduate School of Business and a BS in Marketing Management from De La Salle University, and has completed executive programs at the University of Asia and the Pacific and Asian Institute of Management.
Editor’s note: This Q&A has been edited for clarity and TNGlobal house style. The substance of the interviewee’s responses, including views and attributed claims, has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Flam’s Shourya Agarwal on turning interactive AI content into repeatable enterprise workflows [Q&A]