Malaysia’s SME financing gap is not only about the availability of capital. For smaller merchants, the speed of access, repayment structure and ability of a lender to understand day-to-day business activity can be just as important.
Paydibs recently introduced merchant financing in which repayments are linked to an agreed percentage of weekly payment settlements rather than a fixed installment. Eligible merchants with at least 90 days of continuous transaction activity can receive pre-approved working-capital offers through the company’s merchant portal, subject to assessment and approval by the financing provider.
TNGlobal previously covered Paydibs’ merchant financing launch in Malaysia. In this TNGlobal Q&A, Tee Kean Kang, Chief Executive Officer of Paydibs, discusses how sales-linked repayments change cash-flow risk, how transaction data enters credit assessment, how merchants should compare embedded financing with conventional SME loans, and where payment data could change access to working capital.
Paydibs’ financing model links repayments to a percentage of weekly payment settlements rather than fixed installments. How does that change repayment risk for a small merchant when sales fluctuate sharply from week to week?
Unlike fixed installments, where the repayment amount remains the same regardless of how much a merchant earns, Paydibs’ percentage-based repayment structure is based on sales performance. When sales are lower, the repayment amount naturally decreases, helping to ease cash-flow pressure. When sales are stronger, the merchant contributes more.
For small businesses where cash flow can fluctuate from week to week, this provides a more flexible repayment structure that moves more closely with actual business performance. It can help reduce the pressure of having to meet the same fixed repayment amount during slower trading periods.
Ultimately, the objective is to make financing work more naturally within the merchant’s existing business and payment cycle.
What transaction or business data is considered when assessing whether a merchant qualifies for financing, and how do you avoid disadvantaging newer or smaller businesses with limited transaction histories?
One of the key advantages of Paydibs’ approach is that financing is connected to an existing merchant relationship and business activity, rather than requiring merchants to start from scratch.
Merchants with at least 90 days of continuous transaction activity can receive pre-approved working-capital offers directly through their merchant portal. The offer considers their transaction performance, relevant Know Your Business (KYB) information and automated credit assessment.
This allows financing providers to consider the merchant’s actual business activity alongside the other information required for responsible credit assessment. Transaction data can provide a more current view of how a business is performing, particularly for smaller merchants whose traditional financial records may not always capture the full picture.
Paydibs does not make the final financing decision. Eligibility, financing amount, pricing and repayment terms remain subject to the financing provider’s assessment and approval.
How should merchants compare sales-linked financing with a conventional SME loan or credit line? In which circumstances does each model make more sense?
Merchants should compare sales-linked financing with conventional SME loans or credit lines based on repayment structure, total financing cost, speed of access and how well each option fits their cash flow and funding needs.
With Paydibs merchant financing, repayments are based on an agreed percentage of weekly payment settlements, so merchants repay less when sales are lower and more when sales are stronger. This provides an alternative to conventional financing structures with fixed repayment schedules or predetermined credit limits, particularly for businesses with seasonal or fluctuating revenue.
Paydibs also brings financing closer to where merchants already manage their payments. Eligible merchants with at least 90 days of continuous transaction activity can receive offers directly through the merchant portal and complete the process digitally, with potential same-day disbursement subject to the required documentation and financing provider’s approval.
This makes sales-linked financing particularly relevant for merchants seeking working capital that can move with their business performance, while conventional loans or credit lines may suit businesses that prefer predictable repayments, longer-term funding or an established credit facility. Ultimately, the right choice depends on the merchant’s funding purpose, cash-flow profile and financing terms.
Does linking financing to payment flows create a risk that merchants become too dependent on a single payments provider? What safeguards or portability considerations should businesses look for?
The purpose of linking financing to payment flows is primarily to make access and repayment more convenient by connecting the financing experience to transactions already taking place within the merchant’s existing business ecosystem.
However, convenience should always be accompanied by transparency. Merchants should have a clear understanding of their financing obligations, repayment terms, fees, settlement arrangements and any conditions that apply if they change payment providers.
In the end, merchants should choose financing based on their business needs, cash flow and ability to understand and meet their obligations. Clear contractual terms and transparency are important in making informed financing decisions.
Malaysia has been expanding digital payments among SMEs, but access to working capital remains uneven. Where do you see the largest financing gaps today, particularly among micro and smaller merchants?
One of the biggest gaps we see is not simply access to financing, but access to it quickly and with less friction. For micro and smaller merchants, working-capital needs can arise unexpectedly, while traditional financing processes can involve separate applications, paperwork and physical visits.
Embedded financing can help bridge this gap by bringing working capital closer to the merchant’s existing payment ecosystem. Through Paydibs, merchants can access financing digitally without having to start a separate application or visit a bank, making the journey more seamless.
This allows working capital to become a more integrated part of the merchant’s existing business journey, rather than another separate financial process.
How do you assess affordability when repayments automatically rise with stronger sales? What prevents a merchant from giving up too much cash flow during a high-revenue period when the business may also need to restock or expand?
Affordability is an important part of the financing assessment. The facility considers the merchant’s transaction performance, KYB information and automated credit assessment to determine an appropriate financing offer, with final terms subject to the financing provider’s assessment and approval.
The repayment amount can increase when transaction volumes are stronger, but it remains tied to the agreed percentage rather than automatically taking a larger proportion simply because sales have increased.
Merchants should review the repayment percentage, total financing cost and other terms carefully to ensure the facility is appropriate for their cash-flow needs and business plans.
Looking ahead, how far can transaction data change SME credit assessment in Malaysia? Could payment providers eventually underwrite businesses that traditional lenders still find difficult to assess?
We believe transaction data can play a bigger role in how SMEs are assessed for financing. Transaction frequency, sales volume and payment patterns can provide financing providers with additional, real-time insights into business activity and potential repayment capacity.
However, transaction data should complement, not replace, proper credit assessment, KYB checks and responsible financing practices. Paydibs is a payment provider, while final financing decisions remain with the relevant financing partner.
More broadly, this reflects our vision for Paydibs to go beyond transactions. We started with payments, expanded into business protection through our SME insurance offering with Great Eastern, and now merchant financing helps eligible merchants access working capital to support their growth.
Together, these solutions support a simple journey: help merchants sell, protect what they have built, and grow what they have.
By bringing these capabilities together digitally, we aim to evolve from simply being a payment partner into a growth partner that supports merchants as their businesses grow.
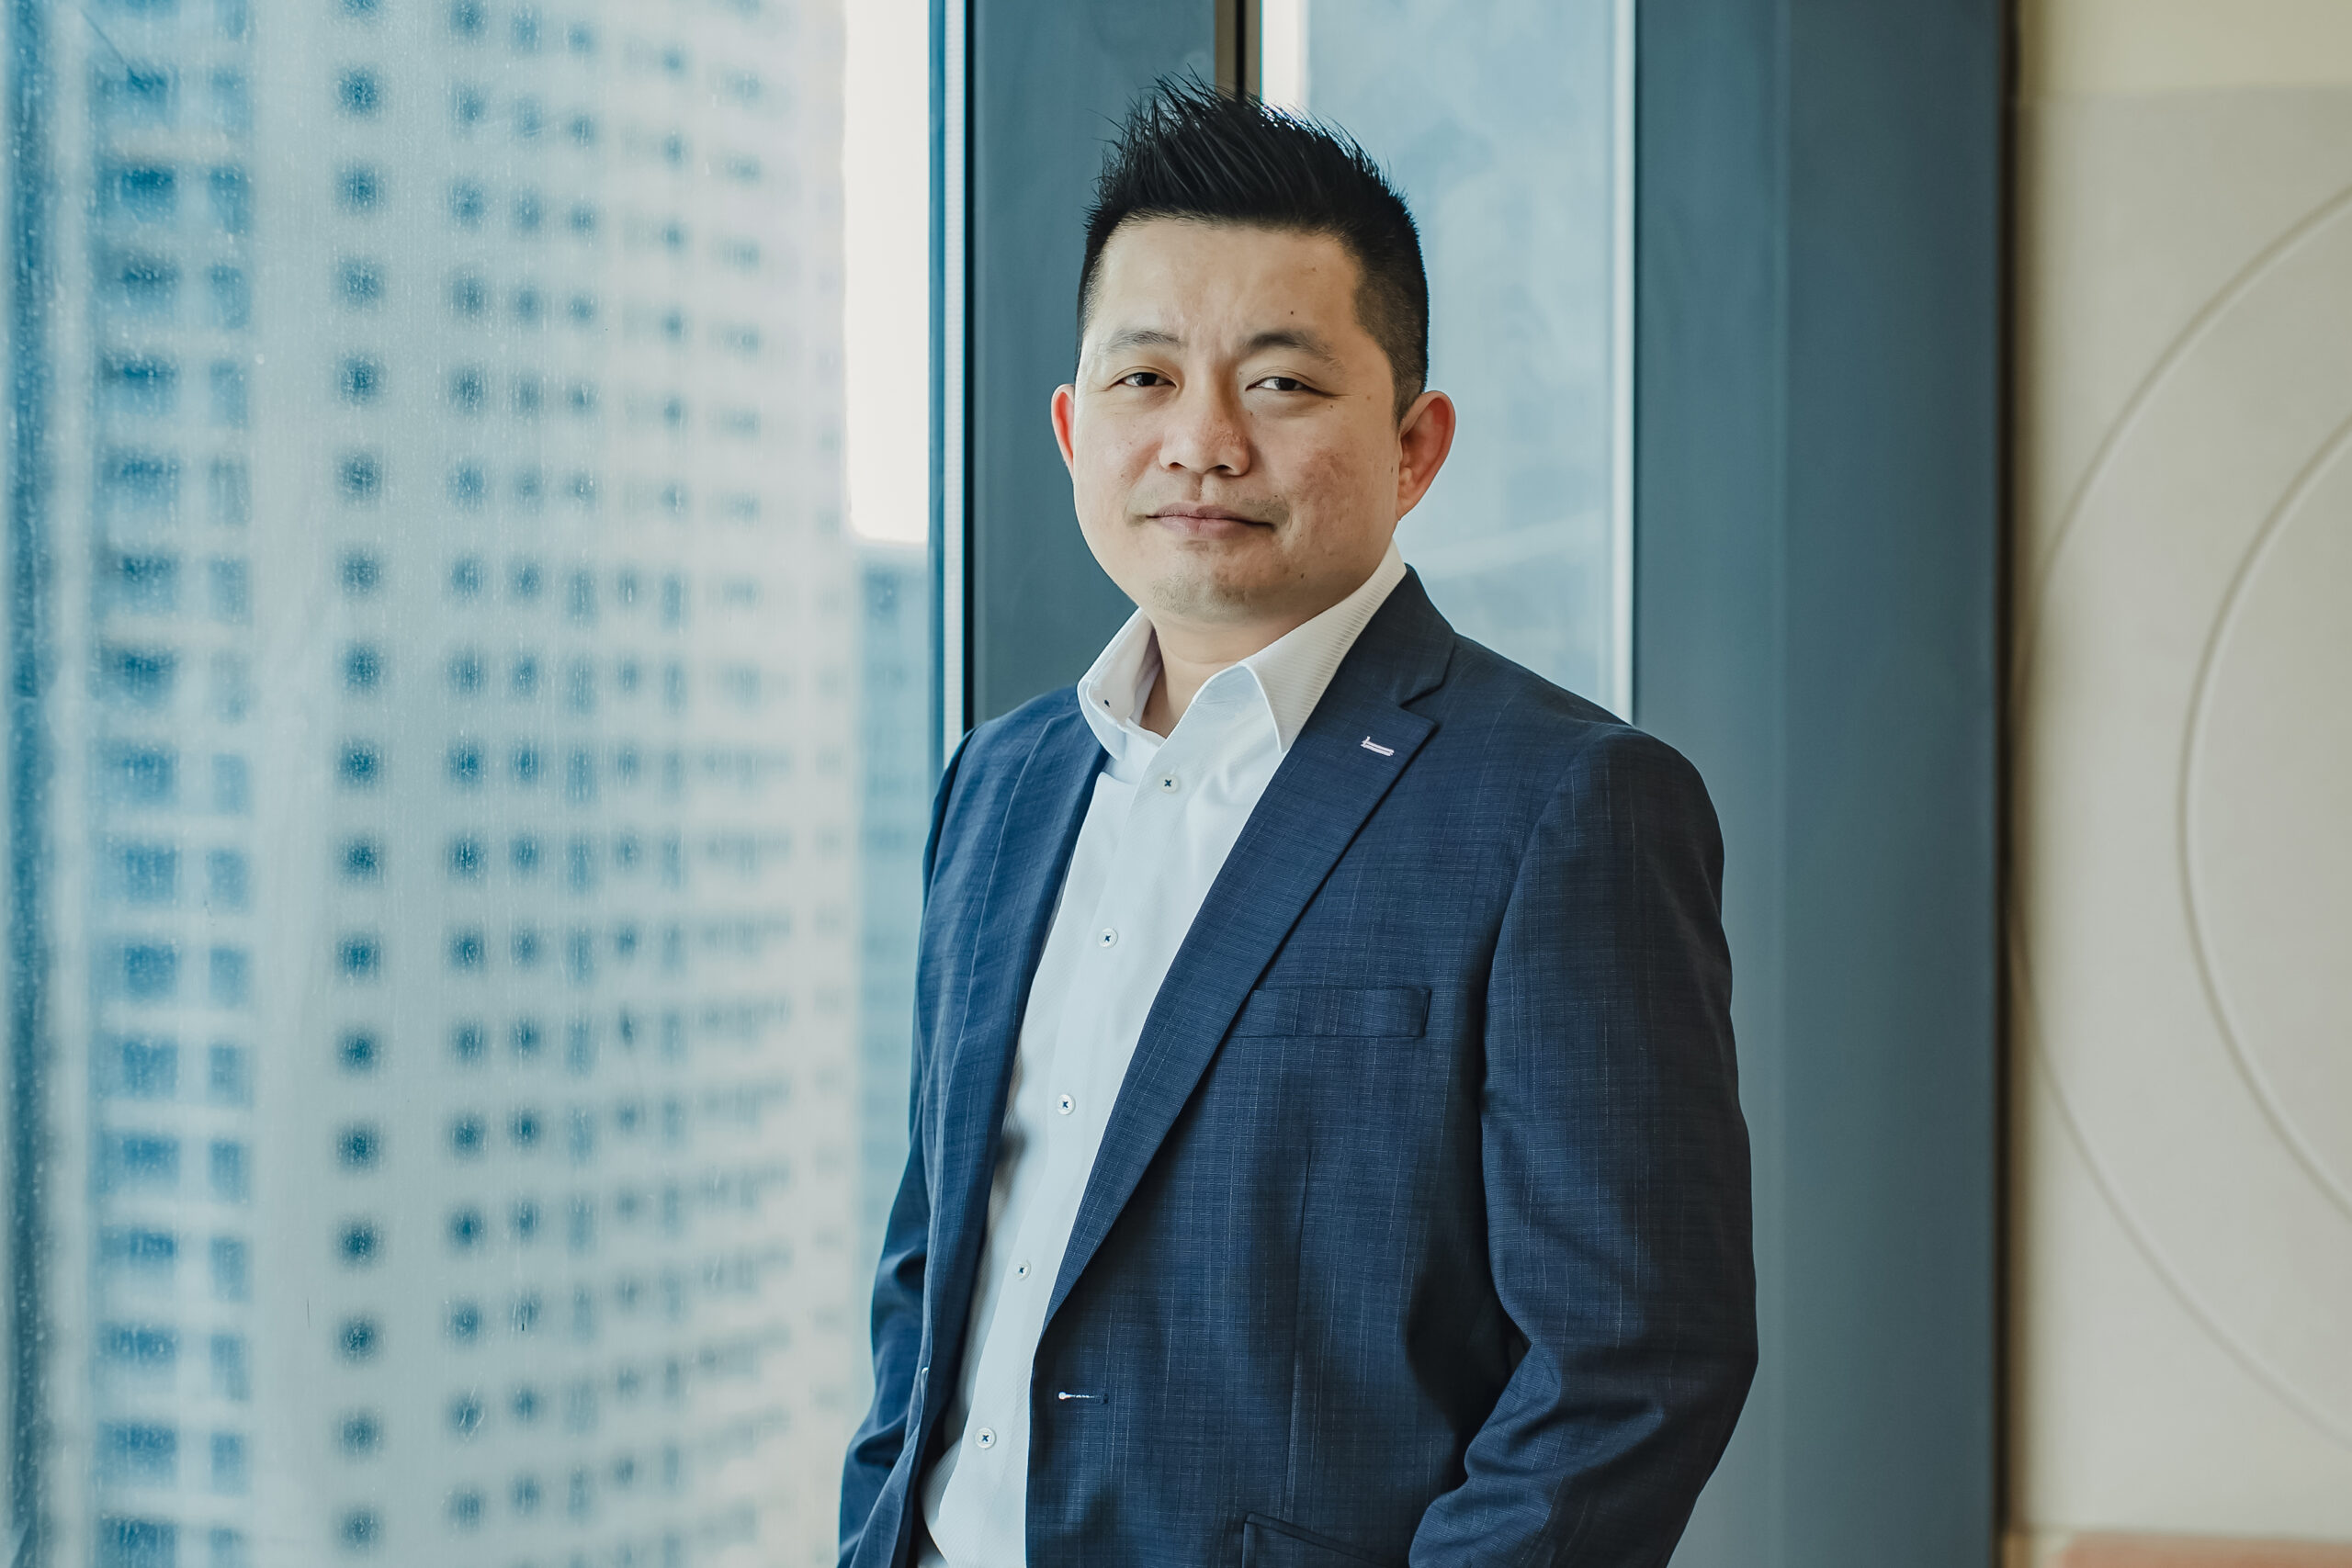
Tee Kean Kang is Chief Executive Officer of Paydibs, a Malaysia-based payments company.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Paydibs launches sales-linked financing for Malaysian merchants