Institutional digital-asset activity in Asia Pacific is increasingly shaped by operating questions around custody, settlement, governance and regulatory structure rather than by basic access alone.
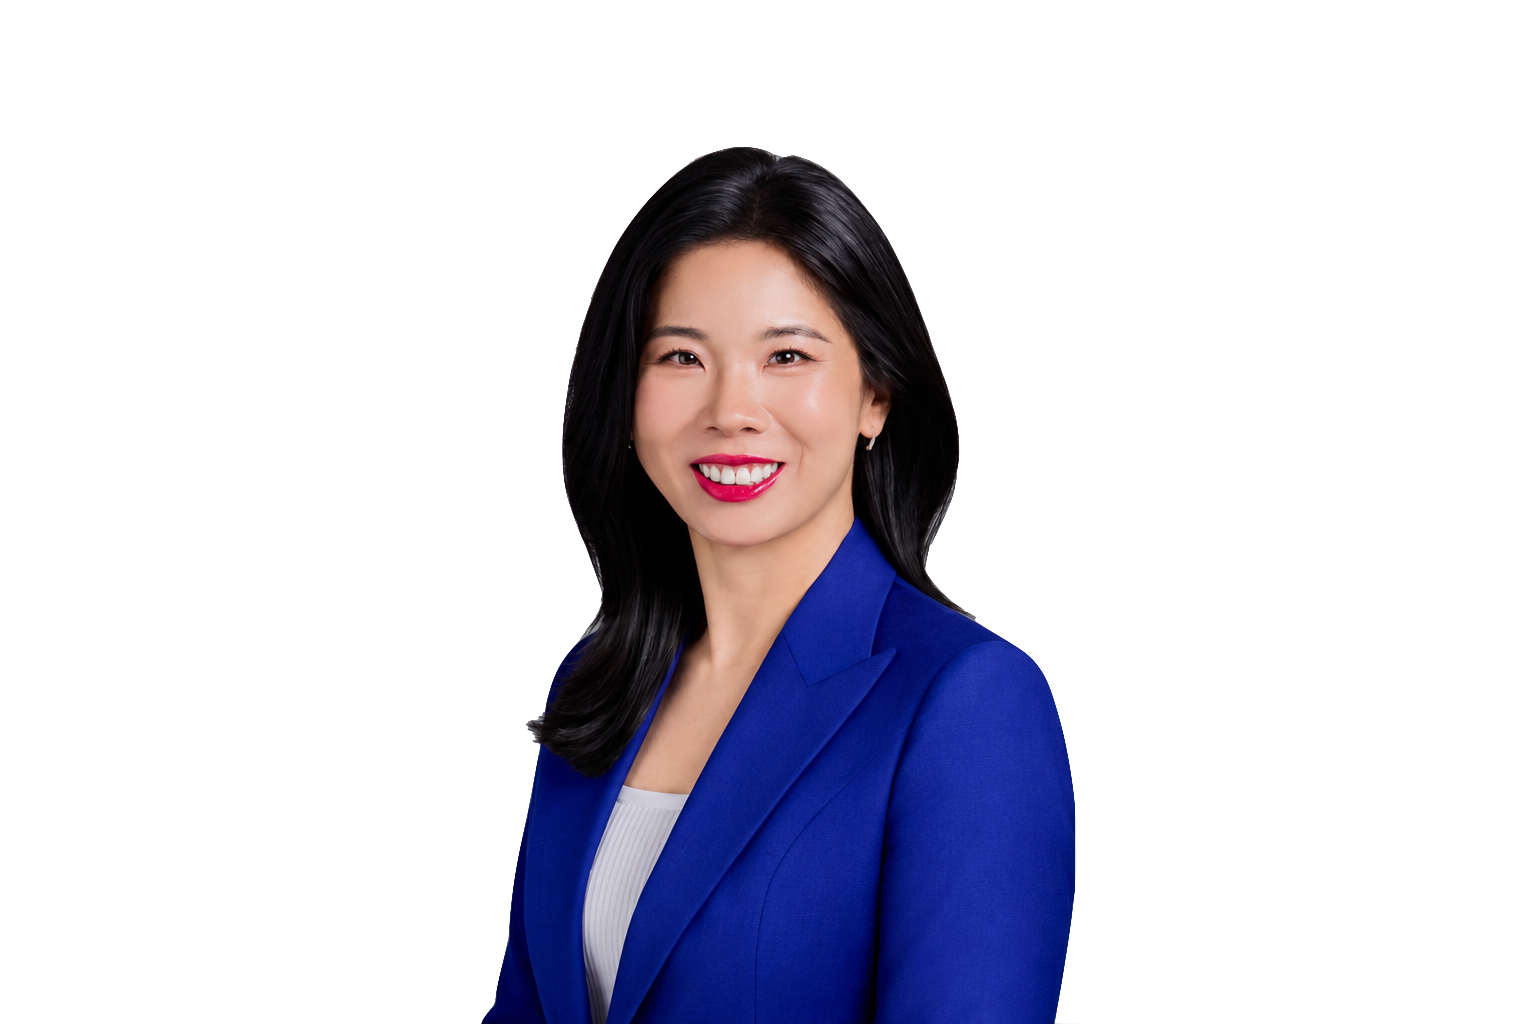
In this TNGlobal Q&A, Angela Ang, Managing Director, APAC and President of BitGo Singapore, discusses how institutional demand is changing, where infrastructure remains fragmented and what banks, custodians and regulators still need to address as digital assets move closer to mainstream financial infrastructure.
What’s changed most in institutional demand over the past 12 to 18 months?
The conversation has moved from “should we do this” to “how do we do this.” Eighteen months ago, most institutional questions were about whether public blockchains should be a part of their infrastructure stack. Now clients are asking about API integrations with their existing systems and how settlement timings line up with their reporting cycles. Risk and compliance teams are asking detailed and more technical questions too, moving from evaluating the suitability of digital assets as an asset class to looking at controls on specific tokens and blockchains. The speed, depth and nature of the conversation has shifted in a way that points to market maturity.
Which parts of Singapore’s regulatory framework matter most for custody, trading, or asset management decisions?
Three things stand out. First, MAS’ regulatory requirements for Digital Payment Token Service Providers (DPTPSs) under the Payment Services Act gives institutions a clear benchmark for counterparty due diligence on digital asset firms. Second, MAS’ application of similar technology risk management standards to banks and digital payment token service providers creates a common baseline for cybersecurity and operational resilience. Third, the new stablecoin issuance framework gives institutions a reference point for what a well-regulated stablecoin looks like, which matters as more of them start using stablecoins for settlement, not just trading. The industry and its regulation will continue to evolve. But Singapore moved early and with sufficient specificity for institutions to translate regulatory clarity into operating decisions.
Where are the biggest infrastructure gaps, custody, settlement, liquidity, operational risk?
Settlement remains the least solved. Custody is further along, and the benchmark for institutional-grade infrastructure is now concrete. At BitGo, for example, private keys can be secured offline in cold storage, with policy-based approvals, address whitelisting, velocity limits and audit trails. Client assets are also held separately from the corporate balance sheet.
But moving assets between custodians, trading venues and fiat rails remains fragmented. Market participants often have to pre-fund venues and reconcile positions manually, creating counterparty exposure, tying up capital and introducing operational risk. Delivery-versus-payment and off-exchange settlement can address these risks today. The remaining gap is market-wide interoperability across venues, custodians and fiat rails.
How are expectations around segregation, governance, and counterparty risk changing after years of market failures?
Institutions ask for proof now, not assurances. They want to understand segregation mechanisms in detail, not just broad concepts. We’re talking about evidence of bankruptcy-remote structures, independent attestations, real transparency into where assets sit and who can move them. Governance questions have gotten more specific, too, who has signing authority, what happens in a default scenario, which entity holds the assets and how is it regulated. Market failures have made those questions unavoidable. They are also the questions BitGo’s operating model was built to answer.
How do institutions manage fragmentation across APAC’s licensing, custody, and token-classification rules?
Institutions standardize what they can and localize what they must. Fragmentation is not going away soon. The institutions moving fastest are building a modular regional operating model that can accommodate local rules, rather than waiting for full harmonization.
At BitGo, our objective is to give clients a consistent custody and control environment while being precise about which legal entity and license supports the client and the services they require. Institutions can then add local legal analysis and market-specific arrangements where required.
Which stablecoin and tokenized asset use cases are moving past pilots, and what still needs to improve?
Many, actually. Stablecoin settlement for cross-border payments and treasury operations is the clearest case with real transaction volume and not just proof of concept. Tokenized money market funds and short-duration credit are close behind, particularly where institutions want collateral that moves faster than the traditional settlement cycle allows. What’s still missing is better interoperability. A tokenized asset issued on one chain, under one regulatory regime, needs to be usable across different providers and venues without a bespoke integration each time.
What role will banks and incumbents play as this infrastructure matures? Build, partner, or both?
Both, and the split is fairly predictable.
Banks have assets that are difficult to replicate: regulated customer relationships, balance sheets, distribution and mature risk-management frameworks. It makes sense for them to build when it comes to product, risk appetite, compliance framework and customer experience.
They’re partnering for the on-chain infrastructure underneath – custody, key management, on-chain settlement – because building that in-house means taking on security and compliance risk that specialist providers have already spent years solving.
That’s not unique to digital assets. Banks don’t build their own card networks either. The institutions moving fastest are the ones that treat this as infrastructure to source, not a capability to reinvent.
What needs to happen for institutional digital-asset activity in APAC to become standard market infrastructure, not a specialist allocation?
Settlement finality and interoperability between digital and traditional rails need to reach the reliability level institutions expect from existing market infrastructure. APAC does not need identical rules, but it needs enough convergence that a global institution can build repeatable operating models. And the track record matters. For every quarter that these systems run without incident, at increasing scale, makes the next allocation decision easier for a risk committee. None of that is a single breakthrough. It’s operational proof, repeated, until digital assets stop being a separate conversation from the rest of the portfolio.
Angela Ang is Managing Director, APAC and President of BitGo Singapore. Before joining BitGo, she was Head of APAC Public Policy and Strategic Partnerships at TRM Labs and previously spent more than a decade at the Monetary Authority of Singapore, where she worked on Singapore’s payments and crypto licensing regime.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
BitGo opens Singapore office as APAC digital-asset business expands