Global Financing for Education (GFE) launched its Pay It Forward education-funding model in Southeast Asia in September, with an ambition to expand access to education while linking participant contributions to future income rather than fixed repayment schedules.
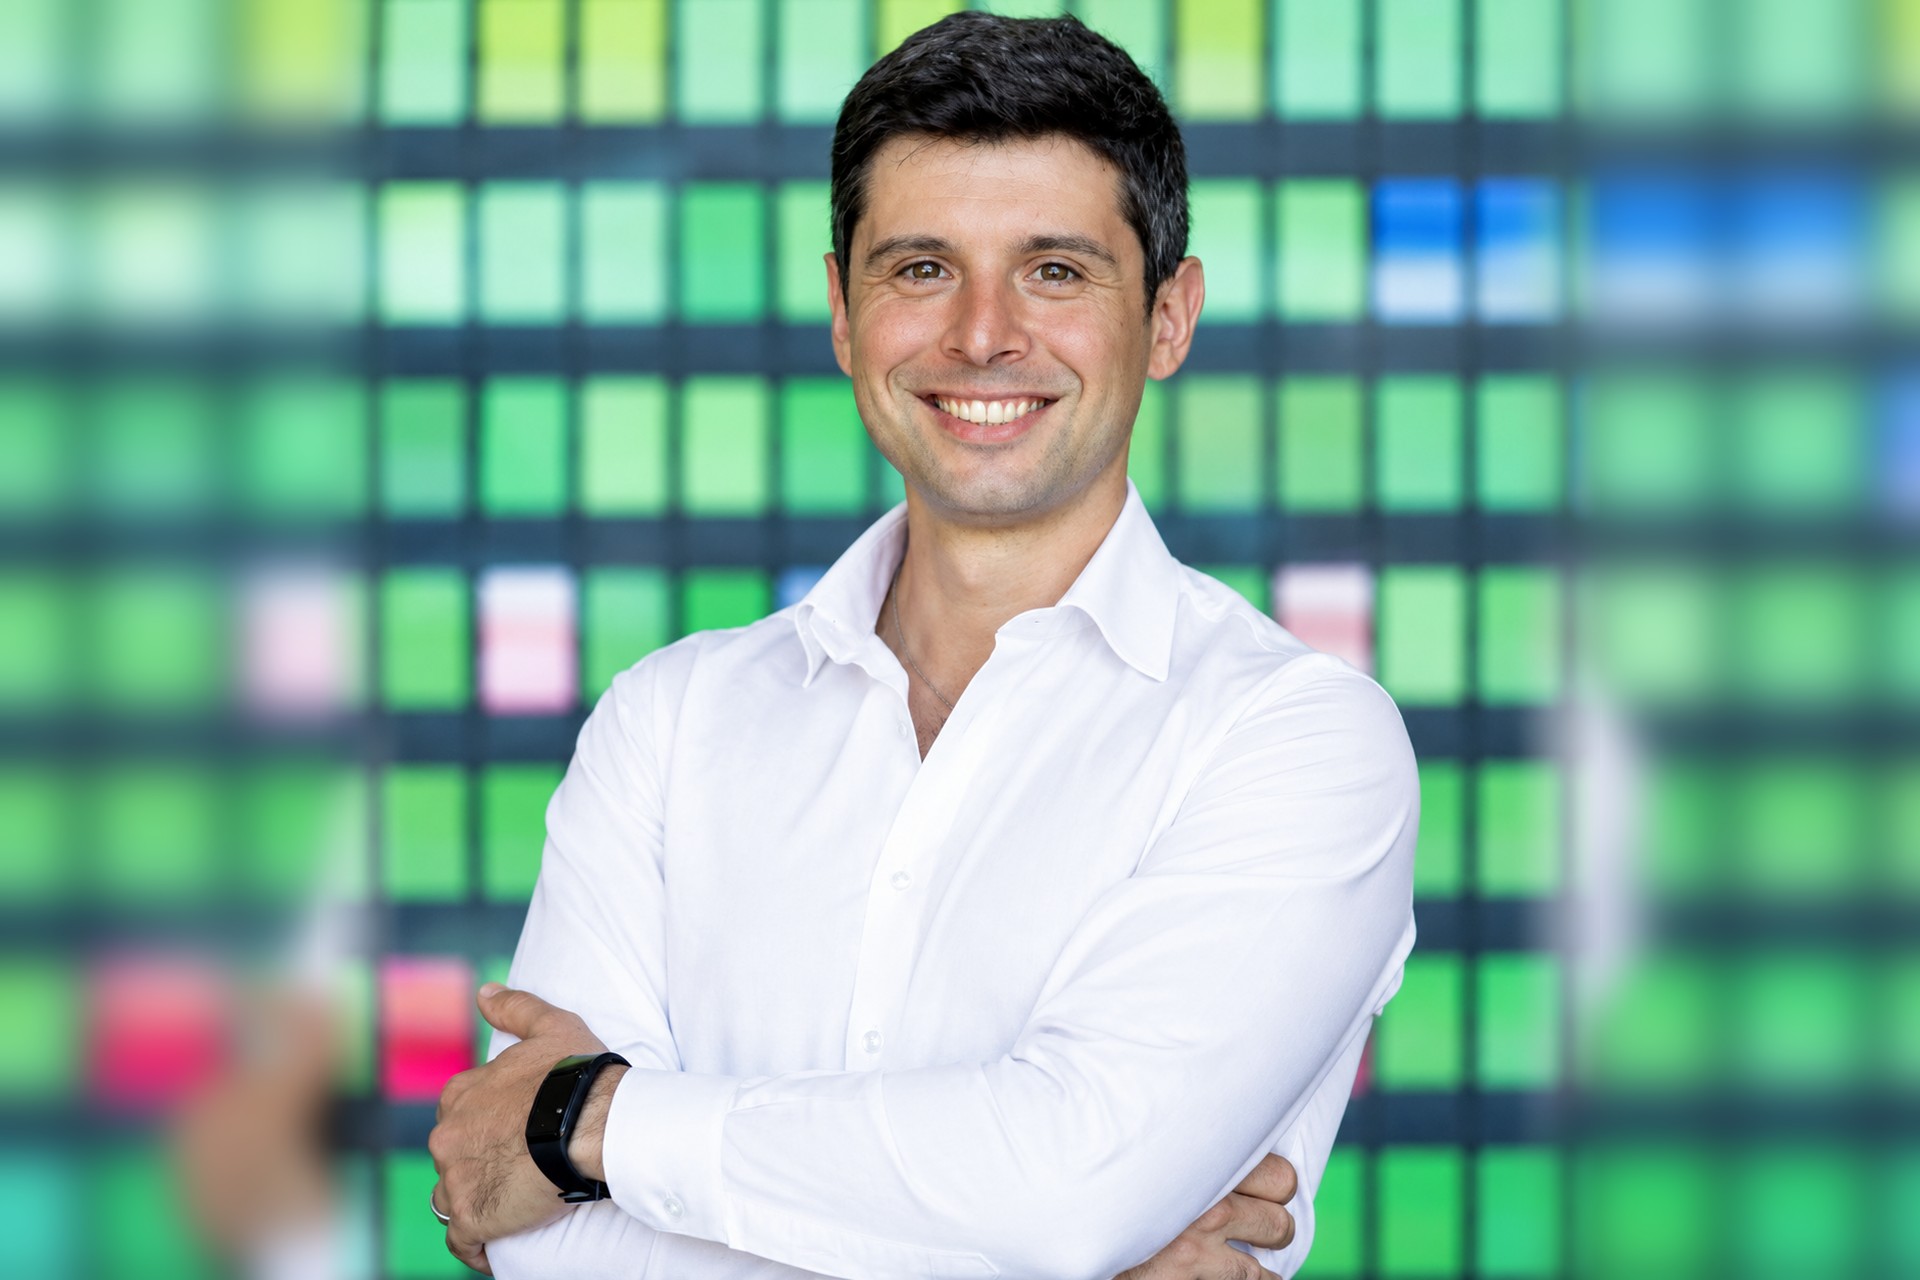
In this TNGlobal Q&A, Mario Ferro, Founder of GFE, offers insights on how eligibility is assessed, how contribution terms are structured, what happens when graduates are unemployed or experience income shocks, and what the model would need to demonstrate before it could scale across ASEAN.
GFE says funding should follow a student’s potential rather than financial history. In practice, how will eligibility be assessed, and which academic, career, financial or other factors carry the most weight?
We look at where students are going, not where they are coming from. Traditional credit asks a fairly narrow question: what assets, income and credit history do you have today? Do you have a guarantor? That is precisely the problem for students. Many have very little financial history because they are at the beginning of their careers.
Our assessment therefore combines the student’s financial circumstances with their educational record, the quality and relevance of the course and institution, employment prospects, expected earning trajectory, career aspirations and personal circumstances. We interview applicants and conduct reference and identity checks rather than relying simply on an automated credit score.
Our aim is to identify people for whom access to education can materially change their trajectory, while ensuring that the resulting Pay It Forward contract is sustainable both for the individual and for the pool. That balance between potential, need, impact and financial sustainability is fundamental to the model.
The Pay It Forward model only asks graduates to contribute once they reach a stable income. How does GFE define that threshold, and how are the contribution percentage and repayment period determined for each student?
We do not believe there should be one arbitrary income number applied across ASEAN. Earning US$500 per month means something very different in Singapore, Manila or Yangon. It also has a different meaning depending on a person’s circumstances.
Instead, affordability is assessed in the context of the member’s income and circumstances. Our contracts currently provide for contributions of approximately 3 percent to 10 percent of income, for periods of between one and 10 years, depending on the amount funded and the risk and expected-income profile. There is also a cap on total contributions, typically twice the original amount funded.
We use a discounted-cash-flow model to test different combinations of amount, percentage and duration. Where appropriate, we offer the student alternative structures, for example a higher percentage for a shorter period or a lower percentage over a longer period. The student can choose between the approved alternatives.
If the monthly commitment becomes unsustainable when contributions begin, we can look at a temporary pause for short-term difficulties or renegotiate terms for more structural problems.
What happens if a graduate takes longer than expected to find stable employment, changes careers, earns below the threshold for an extended period or experiences a significant loss of income after contributions have begun?
That is one of the differences between Pay It Forward and conventional debt.
If someone is studying or unemployed, they are not expected to make an income-based contribution. During that period our current model uses a very small US$1 to US$3 monthly commitment contribution, depending on the country. Once the member is working, contributions become a percentage of actual income.
We call our approach compassionate collection. If someone’s circumstances deteriorate temporarily, contributions can be paused or adjusted. If their circumstances have changed more fundamentally, we can consider restructuring the contract, for example reducing the income percentage and extending the duration.
Because contributions from earlier participants are intended to help fund future students, what assumptions underpin the sustainability of the pool? What would GFE need to see for the model to scale toward its 1 million-student ASEAN ambition?
The million-student ambition should not be interpreted as one pot of money magically recycling itself one million times. Recycling capital is powerful, but it is one component of scale.
Three things have to happen together.
First, education has to produce outcomes: students need to complete, enter employment and improve their earning potential. Second, the portfolio needs sufficient contributions from employed graduates for capital to recycle. Third, GFE needs to continue attracting new capital.
Our ambition is to move education financing beyond a model dependent exclusively on philanthropy. As the portfolio develops a credible track record, we want to complement grants and philanthropic capital with impact and investment capital.
The first US$1 million committed to GFE came from UBS Optimus Foundation, and our first GFE contracts were only disbursed in May 2026. We therefore have to be disciplined about distinguishing ambition from evidence.
How do the initial private investors and foundations participate economically, and how do you prevent investor expectations from creating pressure to select only students or programs with the highest expected incomes?
We are deliberately building GFE to accommodate a spectrum of capital rather than forcing every funder into the same risk-return profile.
At the impact-first end, philanthropic and concessionary capital can support innovation, take more risk and allow us to reach populations that conventional finance systematically excludes. Over time, once sufficient portfolio evidence exists, we expect to be able to attract more return-seeking impact capital as well, as long as they remain committed to impact.
If the only optimization criterion were financial return, the rational strategy would be to finance the safest students studying for the highest-paying professions. That would defeat much of the purpose of GFE.
Our objective is not to maximize IRR. It is to generate enough financial performance to preserve and recycle capital while maximizing educational and social impact.
Waiser provides the technology, assessment tools and infrastructure behind the program. Where is AI used, what decisions remain human-led, and how do you address bias, explainability and data privacy?
Technology helps us process information, identify patterns and eventually make underwriting substantially more efficient. But we do not believe a black-box algorithm should decide whether someone deserves an education.
Today the process combines technology with substantial human review. Applicants provide detailed educational, career and financial information; we conduct an interview, identity and AML/KYC checks and professional reference checks; and a human approval process ultimately determines whether an application proceeds. The technology provides structure and consistency around that process.
As our dataset grows, AI can become particularly valuable in identifying patterns in course outcomes, employment trajectories and portfolio risk, and in helping our team make better-informed decisions. But our principle is AI-supported, not AI-decided.
Historical financial data can encode historical exclusion. We therefore want models that are explainable, regularly tested for unintended bias and subject to human oversight, alongside strong data-protection controls.
ASEAN education, lending, consumer-protection and employment markets differ substantially from country to country. Which regulatory or operational differences are likely to be most difficult as GFE expands?
Absolutely. ASEAN is not one regulatory market, and we should not pretend it is.
The legal classification of an income-linked education contract, consumer-credit rules, cross-border payments, foreign-exchange controls, data protection, collection practices and even the ability to move money to an education provider can differ substantially between countries.
Our Singapore structure gives us a strong regional base, but we assess markets individually and work with local legal and operational partners where necessary.
That may mean the product, contracting entity, payment mechanism or partnership structure differs from one market to another. What should not change are the underlying principles: affordability, transparency, income-linked contributions, appropriate consumer protection and alignment between GFE and the student.
Beyond the amount of financing deployed or the number of students supported, what outcomes will determine whether the model is working?
For us, dollars deployed is an input, not an outcome.
The first question is whether students complete their education. Then whether they find employment, how long that takes, whether their income and career opportunities improve, and whether the education proved economically worthwhile for them.
On the financing side, we will track the proportion of members who are contributing, affordability and delinquency, how much capital is recycled, and how effectively each dollar of external capital ultimately finances education.
Over time this creates another potentially powerful feedback loop. We can observe which institutions and courses actually produce strong employment outcomes and use that evidence to improve both our underwriting and the information available to future students. We are already building toward institution-level employability assessments based on observed graduate outcomes.
Mario Ferro is Founder of Global Financing for Education (GFE), the organization behind the Pay It Forward education-funding model launched in Southeast Asia. Waiser provides technology, assessment tools and infrastructure supporting the program.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Grafilab bets on sovereign AI to take Malaysia’s Neo Cloud ambitions beyond its borders [interview]