Singapore’s shift toward electric heavy vehicles poses a different challenge from encouraging passenger EV ownership. Fleet operators must work out where vehicles can charge, how much power depots can obtain and whether the operating schedule leaves enough time for charging without interrupting deliveries.
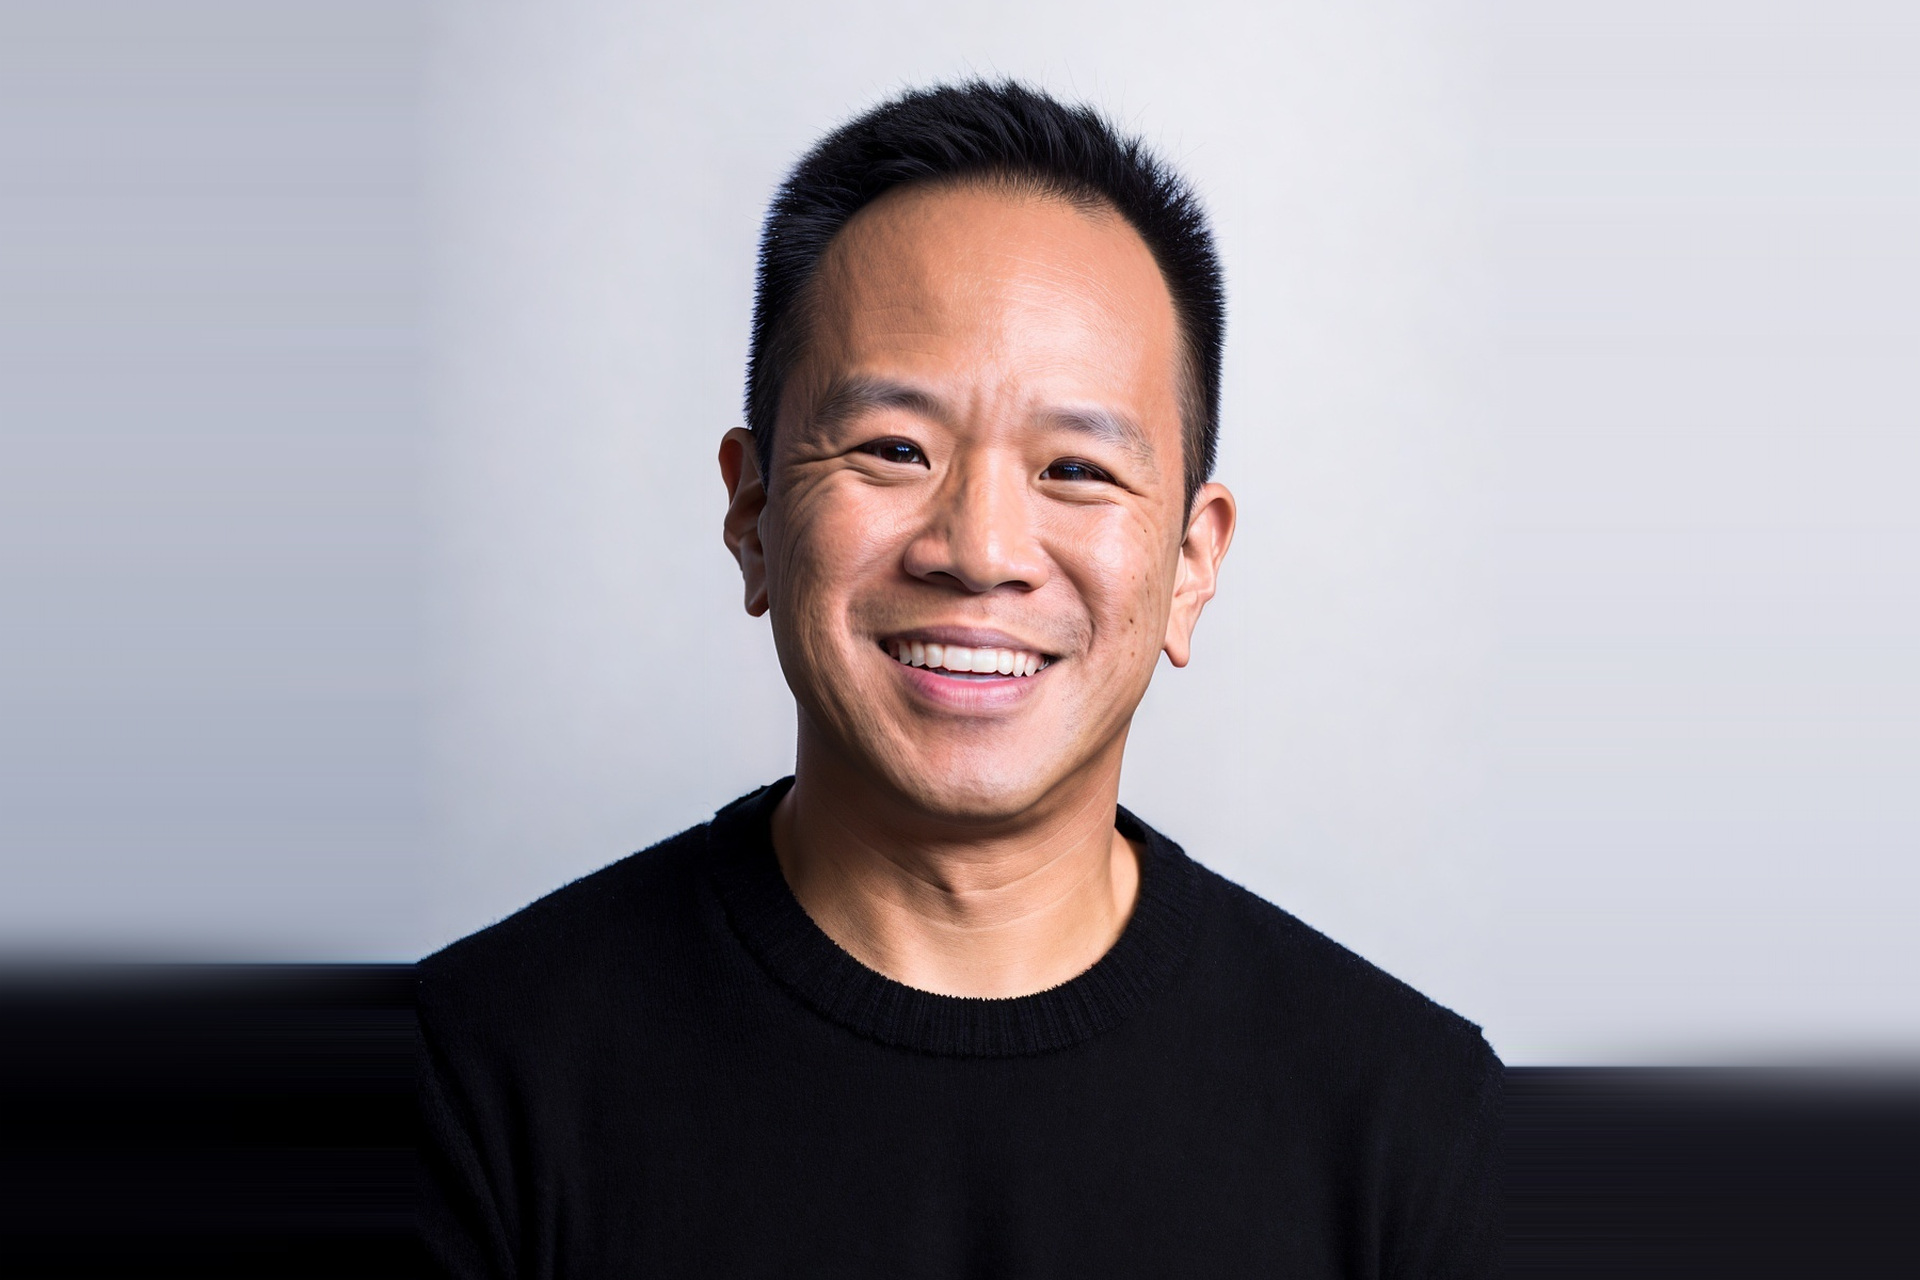
In this TNGlobal Q&A with Jeremy Ong, Senior Manager of LHN Energy and General Manager of LHN Parking, we explore the practical constraints of depot electrification, including grid capacity, physical site layouts, charging schedules and project costs. Ong also explains when rooftop solar can help and when operators may need to retrofit, relocate or use shared charging facilities.
The discussion considers Singapore’s electric-heavy-vehicle incentives and the policy changes that could make long-term fleet investments easier to plan.
As commercial fleets move toward heavier EV adoption, which depot constraints tend to become binding first: available grid capacity, charging hardware, site layout, or something else?
With electric heavy vehicles (eHVs) making up 30% of newly-registered heavy vehicles as of July this year, per LTA, the question for operators has shifted from whether to buy eHVs to where to charge them. With the Ministry of Transport stating in March that only 154 of Singapore’s 298 heavy vehicle charging points were publicly accessible, much of the build-out falls to operators’ own depots.
In that setting, grid capacity is usually the first constraint to bind, and the slowest to fix. A single DC fast charger for an eHV can draw as much power as a small building, so a depot planning several is effectively asking for a new utility connection. Application, design, approvals, and any cabling or substation works can take longer than the lead time on the vehicles themselves.
Site layout comes a close second and is often overlooked. Heavy vehicles need turning radius, queueing space, and dedicated bays, and chargers, cable runs, and switchrooms have to fit around existing circulation. From my work at LHN Parking, I’ve seen how quickly a handful of badly placed bays can create bottlenecks at a busy site. Charging hardware is rarely the binding constraint, as it is the easiest to procure and install.
How should fleet operators estimate the amount of site power they will actually need, particularly when electrification is being rolled out in phases rather than all at once?
Start with operations, not charger specifications. For each vehicle, work out the daily energy it needs based on route distance, payload, and duty cycle, then check how long it is parked and available to charge for. That tells you the energy required and, more importantly, how many chargers will realistically run at the same time.
That second number matters most. What drives the capacity you need is the peak load across the depot, not total energy consumed; twenty vehicles charging in a staggered pattern will require far less capacity than twenty charging at once.
This logic informs how we assess projects at LHN Energy, drawing on a solar portfolio of about 9,900kWp built across Singapore. Before structuring anything, we look at the planned eHV deployment, charging demand, electricity consumption, rooftop solar potential, and the site’s available electrical capacity. Together, these determine the right solar and DC fast charging configuration.
For phased rollouts, we’d recommend sizing the long-lead, hard-to-change items for the end state, such as incoming supply, ducting, switchgear, and space for transformers, while installing chargers in stages as vehicles arrive. It helps to leave headroom, since battery sizes and utilization patterns will change.
Where can on-site solar meaningfully reduce the cost or grid impact of fleet charging, and what are its practical limits for depots with high or concentrated charging demand?
Solar is best understood as a way to lower energy costs, not to remove the need for grid capacity.
It works well where vehicles are parked and charging in daylight hours, such as day-shift fleets or vehicles that return midday. Depots usually have large roofs and carpark shelters, making them natural candidates. We’ve seen the carpark angle firsthand through the solar carport we completed at Goldhill Plaza in August 2025 – delivered in a collaborative effort by LHN Energy and LHN Parking – which put an open-air carpark to productive use. Across our wider portfolio, LHN Energy’s solar systems generate about 15,855MWh of electricity a year.
The limits are physical: roof area is finite, and a fleet of heavy vehicles can consume far more energy each day than a roof can generate. Many fleets can also charge overnight, when there is no sun. Solar does not reduce peak demand at your connection, unless it is paired with storage or charging is scheduled around daylight.
That is why a site assessment is crucial and comes first, looking at roof capacity, structural suitability, and the charging profile together. Our integrated solution, rolled out in September, combines a solar power purchase agreement (PPA), DC fast charging, and project delivery in one plan. Under the PPA, LHN Energy finances, installs, and maintains the solar system, and the business buys the electricity it generates at a pre-agreed rate, typically below grid tariffs, over a term of 10 – 25 years. LHN Energy retains ownership of the system throughout.
Electrical works are the most common surprise. Companies budget for vehicles and chargers, only to discover after that cabling, switchgear, transformer upgrades, civil works, and reinstatement can add significantly to the bill. Approvals, design, and project management time are also easy to miss. For that reason, we scope every installation to be signed off by a Licensed Electrical Worker and approved by BCA and SCDF from the outset, so compliance work is costed upfront.
On the recurring side, the items most often underestimated include:
Which upfront and recurring costs are most commonly underestimated when companies build a business case for depot charging?
- Electricity tariffs, particularly charges linked to peak demand, which can exceed the energy cost itself if charging is unmanaged.
- Charger maintenance, software, and network fees, and downtime when a unit fails.
- The operational cost of vehicles waiting to charge, and of bays taken out of normal use.
Grant support helps, but needs to be modeled carefully. The Electric Heavy Vehicle Charger Grant (EHVCG) co-funds up to 50% of eligible charger installation costs – capped at $30,000 per charger – for the first 500 approved chargers through 2028. It can cover the charger system, licensed electrical worker fees, cabling, and installation. However, it’s reimbursement-based, so businesses must complete the required approval and claims process before receiving funds – which has cash-flow implications.
This is why we’ve folded EHVCG support into the same structure as the solar PPA, charger supply, electrical works, and commissioning. Depending on eligibility, site assessment, grant approval, and final commercial terms, some projects can be structured with zero upfront infrastructure cost. The business case should still be tested without assuming the grant.
How much can charging schedules, load management and vehicle utilization change the economics of an EV fleet without requiring major additional grid capacity?
Significantly, and often at lower cost than adding grid capacity.
Load management is the main lever. With smart charging, a group of chargers can share a limited connection, and the system allocates power according to which vehicles need to leave first. Scheduling charging away from peak periods reduces demand-related charges. Matching charger power to how long vehicles are actually parked also avoids paying for fast charging that’s not needed. A vehicle parked overnight may not need the most powerful charger.
Utilization matters too, and fleets with predictable routes and return times will get the most out of this approach. From LHN Parking, I’ve seen that good site operations come down to understanding dwell time and managing flow, through bay allocation, access control, and data on how vehicles use a site. The same discipline applies to charging.
There are limits, however. Fleets running near-continuous, multi-shift operations have little slack to shift charging and will need more capacity. Smart chargers are also required under the EHVCG, so this capability is increasingly the default.
For older depots or constrained industrial sites, how should operators weigh retrofitting the existing site against relocating or developing a purpose-built charging facility?
I would frame it around four points of consideration: how much it costs to bring enough power to the existing site, how long the operator will remain there, whether the physical layout can work, and how much disruption the business can absorb.
Retrofitting usually makes sense when the electrical supply can be upgraded at reasonable cost, there’s space for charging bays and queueing, and the remaining lease term’s long enough to recover the investment. It can also be staged, which allows operators to learn as they scale. Retrofitting is familiar territory for LHN Parking, where we work with existing carparks rather than greenfield sites, helping property owners upgrade carpark systems for ERP 2.0. On the energy side, LHN Energy’s solar installations span metal-deck, reinforced-concrete and tiled roofs as well as carpark structures, so working with what a site already has is standard practice for us.
Relocating or building with purpose become the more attractive options when constraints are structural – for example, when there’s no room for safe vehicle movement, the roof or ground cannot support the equipment, or the lease is too short to justify the spend.
There’s also a middle path, where operators can use shared or public charging in the interim while their own site’s being prepared. LHN Energy runs public EV charging with partners at sites, including 202 Kallang Bahru and 1557 Keppel Road, which gives us a working view of how shared charging is used day to day.
From a policy and utility perspective, what changes would make it easier for commercial fleets in Singapore to electrify at scale over the next few years?
There are three changes that would make the biggest difference.
First, faster and more predictable grid connections. Operators need clearer visibility of available capacity in industrial areas and more certainty on timelines, because uncertainty over power supply holds up vehicle purchase decisions.
Second, tariffs that reflect how fleet charging actually behaves. If managed, off-peak charging will be visibly rewarded, giving operators a stronger incentive to invest in load management, rather than additional capacity.
Third, simpler coordination across the agencies involved in approving chargers, electrical works, and solar, so operators don’t have to navigate the process separately with each.
On funding, the EHVCG is a strong start. Greater clarity on support beyond 2028 and on what happens once the first 500 approved chargers are reached will be immensely helpful for operators planning longer-term. Faster reimbursements will ease cash flow, and lease tenures on industrial land that match the payback period of charging infrastructure will give operators further confidence to invest.
Overall, the technology certainly exists. What operators really need is clarity on timelines and costs, so that they can plan ahead with confidence.
Jeremy Ong is Senior Manager of LHN Energy and General Manager of LHN Parking, overseeing parking and renewable-energy business development and operations. He has more than a decade of carpark-management experience, previously worked as a mechanical engineer at Hewlett-Packard Singapore, and holds a Bachelor of Engineering in mechanical engineering.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Bitdeer’s Pretesh Dahya on building AI/HPC infrastructure across the US, Europe and Asia [Q&A]