Digital wallets are moving closer to overtaking cards in several Asian markets, but the next phase of payment change is not simply about adding more ways to pay. As transactions become more embedded and less visible to consumers, merchants also have to make trust, authentication and accountability work earlier in the payment journey.
In this TNGlobal Q&A, Konrad Chan, Head of SMB, Asia at Global Payments, discusses what Hong Kong’s wallet adoption may signal for Singapore, where cross-border QR and account-to-account payments still face friction, and how agentic commerce could change authorization and fraud risk. The discussion also touches on BNPL, crypto payments and the operational trade-offs businesses face when supporting local payment methods across Asia-Pacific.
The shift is also part of a wider regional push toward more connected payment infrastructure. TNGlobal recently reported on DBS and Stripe’s partnership around AI and cross-border payments in Asia.
Hong Kong has already seen digital wallets overtake cards in both e-commerce and point-of-sale value. What would need to happen for Singapore to cross a similar threshold, and what could slow that shift?
The tipping point for Hong Kong came from cards moving inside wallets, supported by near-universal QR acceptance and the Faster Payment System. The 2026 Global Payments Report found that digital wallets now account for 41 percent of e-commerce and 45 percent of point-of-sale value there, ahead of cards at 36 percent and 40 percent, respectively.
In Singapore, cards still led at 44 percent of e-commerce and 40 percent of point-of-sale value in 2025, with wallets close behind at 40 percent and 36 percent. We forecast wallets reaching 45 percent of e-commerce and 44 percent of point-of-sale value by 2030, closing the gap with cards.
For Singapore to cross a similar threshold, PayNow and SGQR would need to become genuine alternatives to card rails. That means deeper cross-border interoperability, such as a Singapore wallet working as seamlessly in Bangkok as it does at home, and more diversified wallet funding rather than relying mainly on stored cards.
A new rail will need to win on cost and cross-border reach, not convenience alone. What could slow that shift is also what makes Singapore’s card infrastructure strong: decades of widespread acceptance and a consumer preference for credit over debit that runs at roughly three-to-one by value.
As QR and account-to-account payment systems become interoperable across borders, where does the remaining friction move to?
Interoperable QR standards are stitching the region into a lower-cost, real-time payments corridor. Interoperability solves the visible problem, but it can expose another layer underneath.
Account-to-account payments do not leave the same recovery window as card chargebacks, so verification needs to happen upfront. Providers therefore need stronger authentication, fraud controls and data-quality checks at the start of the payment journey, before a transaction is authorized.
Multi-currency processing and local acquiring also need to work together in real time so a payment can settle across currencies without the consumer noticing the mechanics. In our work with Hong Kong’s HK Express, nearly a quarter of travelers said they would abandon a booking if their local currency was not offered at checkout.
The broader shift is that the more instant and borderless a payment becomes, the more trust needs to be established before the transaction rather than unwound afterward.
If consumers stop consciously choosing a payment method in many transactions, how should merchants think about trust and transparency when the payment layer becomes largely invisible?
The best payment experiences increasingly fade into the background even as the systems behind them become more complex. For merchants, that invisibility can be a goal, but it also raises the bar on trust and security.
Trust does not disappear when the choice of payment method becomes less visible. It shifts toward the merchant’s brand, the reliability of the rails behind the transaction and the controls that allow consumers to understand or challenge what happened.
This becomes especially important as AI begins making purchasing decisions. Merchants will need transparent payment records, verifiable interactions and controls that preserve consumer oversight. Consistent transaction histories across taps, scans and QR payments can become more important precisely because the mechanics are increasingly hidden.
Your data suggests BNPL is settling into a smaller role than once expected, while direct crypto spending remains very limited. What has the market learned about which payment innovations actually change consumer behavior at scale?
BNPL accounted for 4 percent of global e-commerce value in 2025 and is forecast to reach about 5 percent by 2030. That is continued growth, but not the level of adoption once predicted. Direct crypto spending was roughly 0.19 percent of global e-commerce value, still niche next to mainstream payment methods.
One lesson is that innovations change behavior at scale when they align with existing consumer habits rather than trying to create entirely new ones. BNPL’s growth has increasingly come from instalment options embedded inside wallets and card issuers’ own products rather than only from standalone apps.
Crypto faces a different problem: price volatility does not align naturally with merchants that price goods in stable currencies. By comparison, systems such as PayNow, Thailand’s PromptPay and Malaysia’s DuitNow are building interconnected real-time payment networks that can offer an alternative to card rails. The common theme is convenience built around behavior people already understand.
How might agentic commerce change payment authorization and fraud risk when software agents begin initiating or completing purchases on behalf of consumers?
Our 2025 Agentic Commerce Report, based on a survey of 8,000 consumers across seven markets including Singapore and China, showed adoption interest arriving quickly in Asia-Pacific. But enthusiasm and trust are not the same thing. Unauthorized purchases were the single biggest concern raised by Singapore consumers about agentic commerce.
Merchants will need to make trust visible through transparent payments, verifiable AI interactions and controls that remain with the consumer. In practice, that could mean consumer-set spending limits and approval thresholds rather than a blanket handover of payment credentials.
Getting those boundaries right, with liability clear when something goes wrong, will matter more to adoption than the underlying technology alone.
For businesses operating across several APAC markets, when does supporting more local payment methods improve conversion, and when does it simply create more operational complexity?
Payment preferences vary significantly by market. In Singapore, card schemes remain deeply established, while in Malaysia bank transfer is a leading e-commerce method. That means checkout strategy cannot be one-size-fits-all across the region.
More complexity, rather than more conversion, is created when a business adds a payment method that lacks meaningful local penetration. Complexity also rises when smaller businesses have to manage different payment tokens, currencies and banking relationships across several markets.
The case for adding a local method is strongest when it matches established consumer behavior and can be supported without creating a separate operational stack for every country. The challenge for regional merchants is therefore not to maximize the number of logos at checkout, but to choose methods that matter locally while keeping fraud management, authorization and settlement manageable.
What metrics should merchants use to judge whether a payment experience is genuinely becoming better, beyond transaction approval rates and checkout conversion?
Currency and payment-method coverage at checkout is one underused measure. Our work with HK Express found nearly 25 percent of customers would abandon a travel booking if their local currency was not available. That is lost volume a merchant may never see in a checkout-conversion dashboard because the customer leaves earlier.
Settlement speed is another. In one customer case, ipaymy shortened settlement times after consolidating fraud prevention, authentication and reporting onto a single payments platform. That improvement shows up in cash flow rather than in conversion alone.
Fraud loss as a share of payment volume can also be more useful than looking only at absolute fraud figures. Merchants should also examine how many steps customers need to complete a purchase and how well transaction records carry through after payment. A transaction that authorizes quickly but leaves a customer chasing a receipt or refund has not removed friction; it has merely moved it somewhere less visible.
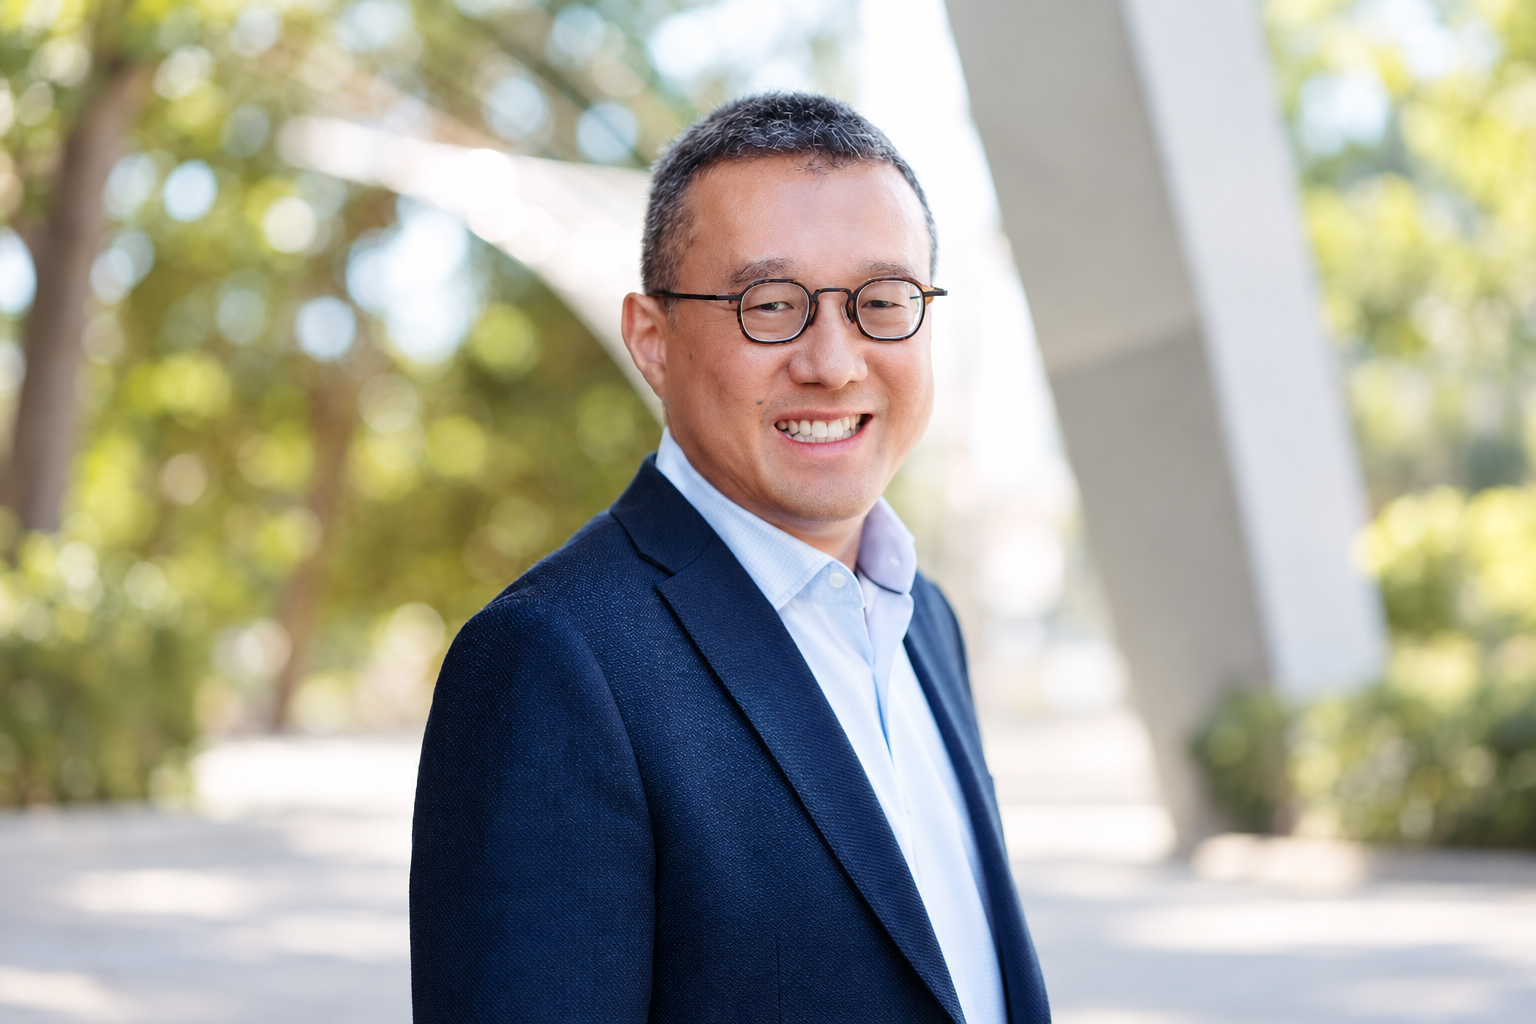
Konrad Chan is Head of SMB, Asia at Global Payments and is responsible for small and medium businesses across the region. He has been with the company’s Asia-Pacific business since 2006. He most recently served as President, North Asia, overseeing sales and business activities in Greater China as well as operational and compliance areas in Asia. Earlier, as Senior Vice President for Operations and Products, he led the launch of a mobile payment acceptance solution and the company’s Premier customer service proposition.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Mario Ferro on how GFE’s Pay It Forward model could scale education funding across ASEAN [Q&A]