Malaysia-based automotive platform CARSOME reported its tenth consecutive positive-EBITDA quarter earlier this year. TNGlobal asked Eric Cheng, Co-founder, Chairman and Group Chief Executive Officer of CARSOME, what has changed in used-car retail, inventory management, financing and aftersales as the company has expanded across Southeast Asia.
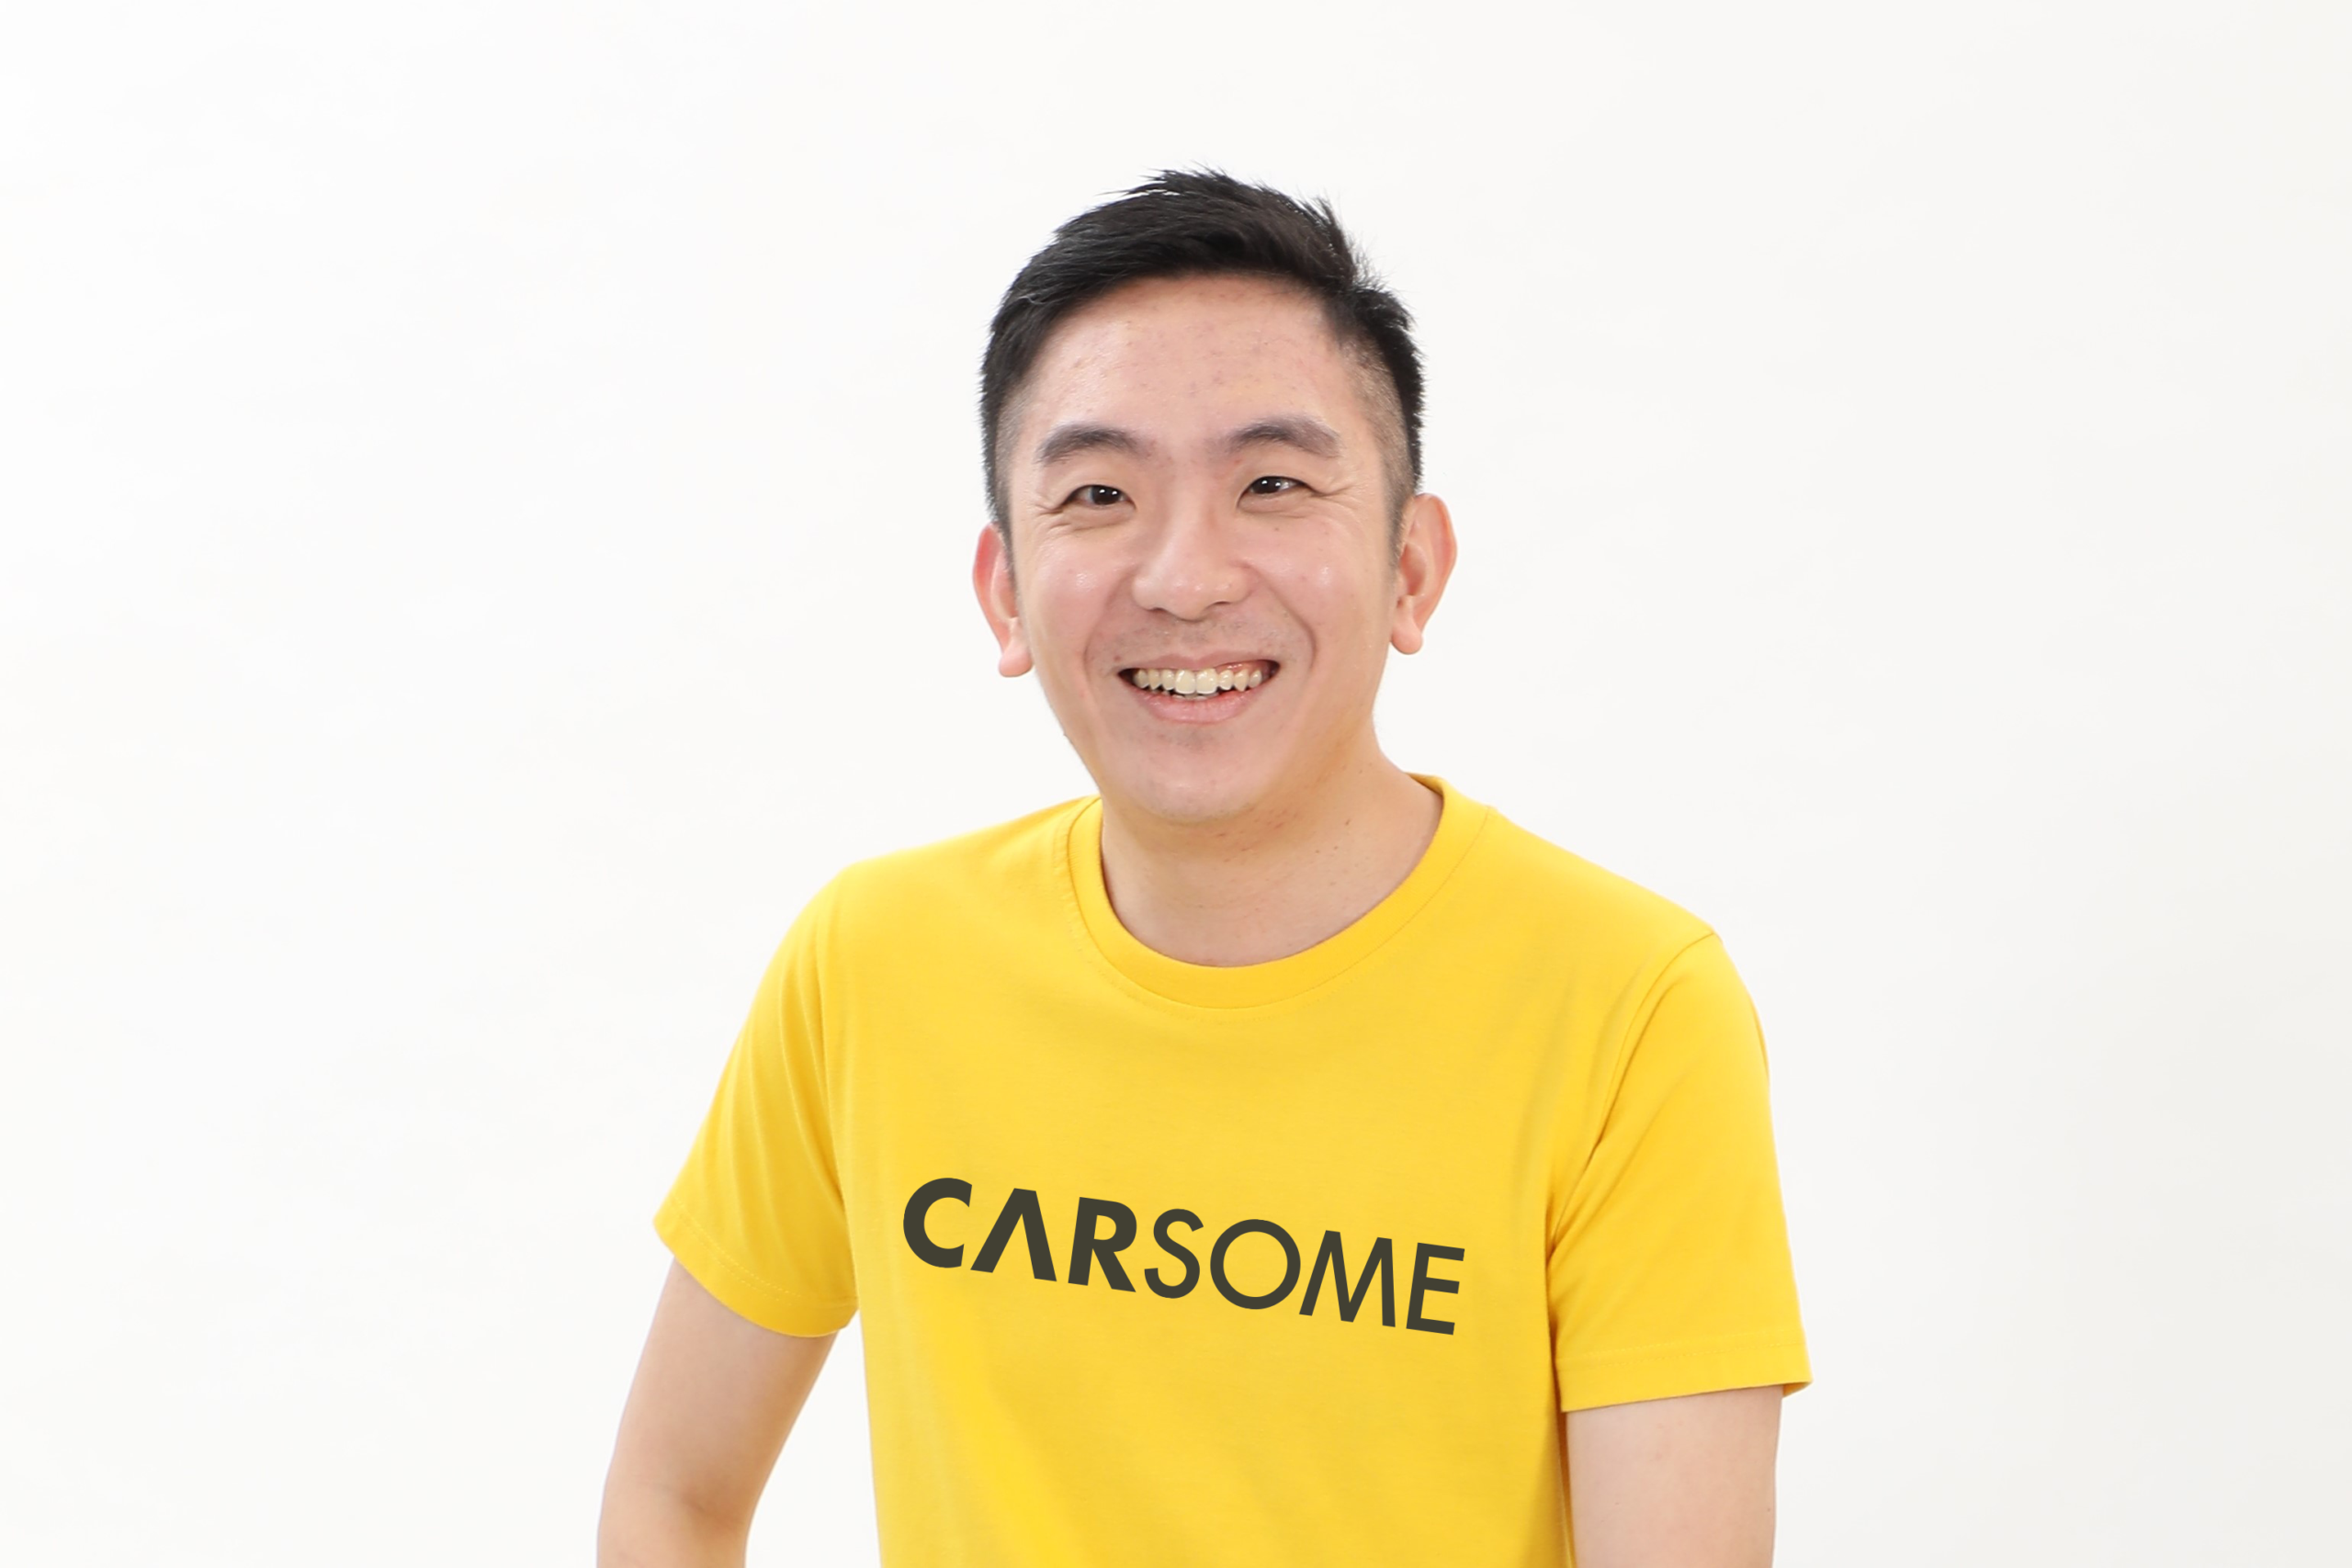
CARSOME has now reported ten consecutive positive-EBITDA quarters. What has changed most materially in the operating model over that period, and which improvements have had the biggest effect on unit economics?
The biggest change has been how we think about growth. In the earlier years, it was naturally about building scale, getting more inventory, building awareness and establishing our presence in the market.
As the business matured, we started looking much more closely at how all the different parts of the ecosystem work together to improve both the customer experience and the economics of the business.
A few things have made a big difference. For one, we’ve become much more sophisticated in how we price and manage inventory. It’s about acquiring the right vehicles at the right price, putting them through the right sales channels and, ultimately, reducing how long they sit in inventory.
We’ve also continued to strengthen our refurbishment and inspection capabilities, which gives us greater control over vehicle quality and margins. And because we now have a broader ecosystem across retail, financing, aftersales and dealer services, we’re able to create value at multiple points in the customer journey beyond the margin on the car itself. So, when we look at positive EBITDA, I wouldn’t say there was one big initiative that got us there. It’s really the result of thousands of smaller improvements across procurement, logistics, refurbishment, sales conversion, financing attachment and cost discipline that have added up over time.
Used-car marketplaces have to balance inventory availability with capital efficiency and pricing discipline. How has CARSOME changed the way it acquires, prices and turns inventory as the business has scaled?
I think one of the biggest improvements as we’ve scaled is our ability to make better, more data-driven decisions throughout the vehicle journey, from the moment we acquire a car to the moment we sell it.
For example, on the acquisition side, we’re now much more precise about what we’re willing to pay for a vehicle. We look at historical transaction data, current demand, depreciation patterns and what’s happening in specific local markets to determine the right buying price. We can also adjust those prices daily as the market moves. That helps us make better decisions upfront, and sets the economics right from the moment we buy.
We’ve also become much more proactive about where we allocate inventory. Instead of looking at inventory as one large pool, we’re increasingly directing vehicles to the markets and sales channels where we see the strongest demand. That helps improve sell-through while keeping us disciplined on pricing.
And then there’s inventory velocity, which is really important in this business. Every additional day a car sits in inventory comes with financing, storage and depreciation costs. So we’ve put a lot of focus on improving everything from demand forecasting and inspection efficiency to refurbishment turnaround and retail conversion.
So ultimately, the goal isn’t to have the biggest inventory. It’s to have the most productive inventory, the right cars, in the right place, moving at the right pace.
Retail and financing are both contributing to growth. How do you think about the role of financing in improving customer conversion without creating excessive credit or affordability risk?
Financing is really important because, for many customers, the decision isn’t just about whether they can afford the price of the car. It’s also about whether the monthly payment makes sense for their financial situation.
So, for us, financing has always been about enabling responsible vehicle ownership, rather than simply trying to maximise the number of loan approvals. Of course, conversion is important, but we also want to make sure customers are taking on financing that is appropriate for them and sustainable over the longer term.
That’s why we work closely with our financial institution partners and use data to better match customers with financing options based on their profile and repayment capacity. Affordability assessments, risk management and responsible lending are all important parts of that process.
We’ve also seen financing become a meaningful part of the customer journey. Our in-house financing attachment rate has increased from 14.54% in YTD August 2025 to 21.93% in YTD August 2026, with more customers choosing to finance their vehicle purchase through CARSOME. This reflects the growing role of financing in helping customers complete their vehicle purchase.
So, from a business perspective, financing helps remove friction from the buying journey. But from the customer’s perspective, it’s really about making vehicle ownership more accessible and manageable. The important thing is making sure that growth in financing comes alongside responsible lending and healthy portfolio performance.
Trust remains one of the biggest friction points in used-car transactions. Which investments in inspection, warranties, aftersales or pricing transparency have produced the clearest measurable impact on customer behavior?
Trust is the foundation of the used-car business. When someone is buying a used car, they’re making a significant financial commitment, and naturally, they want to know what they’re getting, whether the car is in good condition, whether the price is fair, and what happens if something goes wrong after the purchase.
I think one of the biggest things we’ve done is standardize the way we inspect and refurbish vehicles. Every Carsome Certified car goes through the same inspection standards and refurbishment process. It gives customers much more confidence because they have greater visibility into the condition of the car, while we can maintain a more consistent quality standard across the vehicles we sell.
Our warranty and aftersales support also play an important role. Buying a used car can feel like a bigger risk when you’re not sure what happens after you drive it out of the showroom. Having support and coverage after the transaction helps give customers that additional peace of mind.
Pricing transparency is another important piece. Customers today expect to know what they’re paying for and why, so being clear and competitive on pricing helps reduce uncertainty and makes the purchase decision easier.
And ultimately, we look at customer behaviour to see whether these investments are actually making a difference. From October 2025 to August 2026, our Buy Car segment maintained an average Google Review score of 4.4/5 , giving us a strong signal how customers are experiencing the journey. So, for us, trust isn’t really one feature or one initiative. It’s the combination of giving customers more confidence before they buy, and making sure we continue to support them after they drive away.
Southeast Asian markets differ significantly in vehicle ownership patterns, financing access, regulation and consumer expectations. Which parts of the CARSOME operating model transfer well across markets, and which need to be localized substantially?
There are a few things that are universal. At the end of the day, customers want three things: transparency, convenience and confidence. Those needs don’t really change just because you cross a border.
So, the fundamentals of our operating model are quite transferable, things like standardized vehicle inspections, data-driven pricing, quality assurance, refurbishment and a more seamless digital customer journey.
But Southeast Asia is also incredibly diverse, and that’s where we need to be much more local. Financing penetration can be very different from one market to another. Regulatory requirements vary, and consumer preferences around brands, vehicle segments and even how long people typically own their cars can be quite different between neighbouring countries.
So we don’t believe in taking exactly the same playbook and applying it everywhere. The underlying infrastructure and operating discipline can be standardized, but the way we execute has to reflect the local market.
That could mean adapting the financing products we offer, how we engage dealers, our marketing approach, our compliance processes, or even the mix of vehicles we carry. For us, it’s really about finding that balance: standardize what creates consistency and efficiency, while localizing what needs to reflect the customer and market.
As more of the transaction journey moves online, where do customers still strongly prefer physical interaction, and what does that tell you about the limits of a fully digital automotive marketplace?
Digital technology has definitely made the car-buying journey much more convenient, but I don’t think buying a car will ever be a completely digital decision. It’s still a big purchase, and there’s an emotional element to it as well.
Customers are increasingly comfortable doing a lot of the research online. They can compare vehicles, explore pricing, apply for financing and even make a reservation without stepping into a showroom. We see that in our own customer journey, with 63.26% of C2B leads coming through online and website channels, showing how digital is increasingly becoming an important starting point for customers.
But when it comes to making that final decision, many customers still want to see and experience the car for themselves. While customers can complete their purchase online, offline touchpoints such as showroom visits, inspections and test drives continue to play an important role in the journey.
The same applies on the seller side. For someone selling their car, having a physical inspection can provide that additional reassurance that the valuation is based on the actual condition of their vehicle.
So, I don’t think the future is about choosing between digital or physical. It’s really about bringing the two together. Technology should make the journey faster and remove unnecessary friction, while physical touchpoints can provide the reassurance and confidence customers need at key moments.
Ultimately, customers should be able to move seamlessly between digital and physical depending on what works for them. That’s what we mean by an omnichannel experience.
What role is data and AI now playing in areas such as vehicle pricing, inspection, lead qualification, inventory planning or financing? Where do you still believe human judgment remains essential?
Data and AI have become increasingly important for us, particularly as we’ve scaled. When you’re operating at this kind of volume, you simply can’t rely on intuition alone, you need data to help you make faster and more consistent decisions.
Pricing is probably one of the clearest examples. Our machine learning models can look at large volumes of transaction data, market trends and demand patterns to help us arrive at more accurate vehicle valuations. We’ve seen this contribute to improvement in valuation accuracy and a reduction in pricing variance, and, ultimately, better pricing decisions across our inventory.
The same applies to inventory planning. Predictive analytics can help us identify which vehicle categories and models are likely to see stronger demand, which helps us make better decisions around what we acquire and where we allocate it.
But I think it’s important to recognize where technology has its limits. A used car isn’t just a set of data points. Its condition, a particular local market situation, customer preferences or even the dynamics of a negotiation can sometimes require experienced human judgment.
So, we see AI as an augmentation tool rather than a replacement for people. The idea is to give our teams better information and help them make decisions faster, while keeping human oversight where judgment, accountability and customer trust really matter.
Looking ahead, what do you think will separate sustainable used-car platforms in Southeast Asia from businesses that can grow transaction volume but struggle to build durable economics?
I think over the long term, scale on its own won’t be enough. In this industry, you can grow transaction volumes quite quickly, but what really matters is whether you can do that sustainably, with healthy unit economics, disciplined capital allocation, strong customer trust and operational excellence.
For us, that means being good at the fundamentals: sourcing the right inventory, pricing vehicles accurately, managing risk responsibly and giving customers an experience they can trust. But it also means being able to create value beyond the initial vehicle transaction, through things like financing, warranties, aftersales and trade-ins.
We’re already seeing that broader ecosystem become increasingly important to the industry. And the opportunity is significant. The Southeast Asia used-car market is projected to grow from USD 69.73 billion in 2025 to USD 102.37 billion by 2031, representing a 6.61% CAGR from 2026 to 2031. What’s interesting is that the growth is not just coming from vehicle transactions. Financing, insurance, certified pre-owned programmes and digital sales channels are all becoming more integrated into the customer journey.
Technology will obviously continue to play a big role, but I don’t think technology on its own is a competitive advantage anymore. What’s harder to replicate is the combination of technology with the operational infrastructure, customer trust and ecosystem we’ve built over time.
So, ultimately, our focus isn’t simply on facilitating more transactions. It’s about building a profitable ecosystem around the entire vehicle ownership journey and doing that in a way that creates value for customers while keeping the business sustainable over the long term.
Editor’s note: This Q&A has been lightly edited for clarity and TNGlobal house style. The substance of the interviewee’s responses has been preserved.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more conversations in our TNGlobal INSIDER and TNGlobal Q&A and Interviews archive.
Malaysia-based car e-commerce CARSOME reports $8.3M quarterly EBITDA in Q2