Vietnamese banks are experimenting with AI, but few of those projects reach production. According to audax, a Singapore-based digital banking platform, the next stage for banking is agentic banking, but only with governance strong enough to keep pace with new rules of State Bank of Vietnam, the country’s central bank.
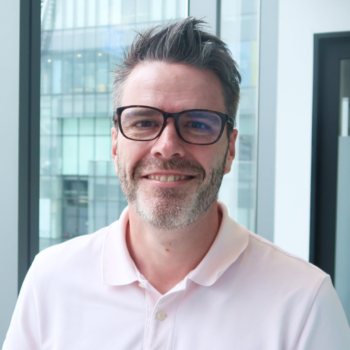
In an interview with TNGlobal, audax Chief Commercial Officer Mike Breen noticed AI adoption in the banking industry in Vietnam has often focused on customer-service chatbots. Meanwhile, a young, well-educated, and digitally native population is reshaping expectations. The opportunity for Vietnamese banks extends beyond answering questions to helping customers.
In the interview, he also shared his views on credit risks, fraud decision management, customers relationship management, among others.
Below are the edited excerpts:
Why should banks utilize AI further?
AI can help banks deliver more relevant services and reduce the effort customers spend managing their finances. AI agents can help move banking towards completing tasks and achieving outcomes. Customers are already building agents to manage their financial lives: tracking their day-to-day processes, forward orders, receivables and taxes.
The opportunity for agentic banking is moving from experimentation towards mainstream, however, banks need to consider how their services will work securely with AI assistants. They must retain control over access, customer consent, and approvals with internal traceability, audit, and compliance as hygiene.
JPMorgan said it was blocking external AI agents that access customer accounts through shared login credentials. That does not mean agentic banking has failed or that access will remain restricted indefinitely.
For me, it shows why identity, permissions and customer authorisation are essential. The opportunity is to make banking easier while protecting customer trust.
How are you going to apply AI in credit risk decisioning, fraud decision management, and relationship management? As AI steps in, how do you make sure that banks still retain relationship management with their customers?
Our focus is on giving banks the data, integration, and governance foundations to apply AI across customer engagement, banking operations, and decision support. That creates opportunities in areas such as relationship management, credit assessment and fraud management, depending on each bank’s priorities and readiness.
But it is one thing to build one or two individual AI cases. The question is how banks can scale to many use cases while reconciling and creating oversight of decisions being made by AI. Ultimately, banks are risk management companies. If you let AI operate without proper oversight, there will be a big problem.
Our approach to solving this challenge is the audax AI Control Plane. Amongst an extensive feature set, it manages risk, governance and control, and provides traceability of AI decisions and actions inside the bank. It also gives the bank full control of what AI is and is not allowed to do on its own.
It can make a decision autonomously, but we also provide the capability for human approval or human oversight before the system learns and trains further.
The AI gap right now is not the use cases, which will come and go. It is in the governance, risk management, auditability, traceability and regulatory compliance of AI in a regulated environment. Regulators across the region are setting clearer expectations for responsible AI adoption.
Singapore’s MAS issued its Guidelines on Artificial Intelligence Risk Management for Financial Institution in Oct 2026. Hong Kong’s HKMA established the “ART” Framework in the same month. Australia’s APRA called for stronger AI governance and risk management in April 2026. In Vietnam, the State Bank of Vietnam issued Circular 53/2026/TT-NHNN, which sets out safety requirements, risk management requirements and deployment conditions for AI systems in the banking sector. The circular takes effect on November 15, 2026.
What opportunities does audax see in Vietnam?
We see opportunities amongst a large number of incumbent banks. That covers a broad spectrum, although our focus is primarily on mid-tier and larger banks. From multiple conversations, we are seeing strong interest from Vietnamese banks in modernization and how it can support business priorities.
Our partnership experience also shows how important cultural alignment is. The bank needs the right mindset when it comes to managing change. An incumbent bank has a lot of established processes and deeply embedded ways of working.
When asked to change, individuals may question why things need to be done differently when existing processes still work. Change brings uncertainty and risk. So the organizational behavior of the bank is important. Technology is an outcome of business transformation. It is not just about replacing technology. The bank has to understand how it wants to change, and that starts with leadership.
Banks can learn from each other. But simply replicating the same technology blueprint brings risk of creating a banking proposition that lacks differentiation. Each bank needs an approach shaped by its customers, business priorities and starting point.
The state bank wants to modernize the banking system, and its biggest concern with real-time payments is money laundering. How can audax help?
I don’t think you’ll ever wholly eliminate money laundering anywhere with a single capability or service. It’s an ongoing fight. We support that fight by providing a flexible platform that enables banks to respond quickly to continuously adapt to the threat of money laundering and fraud.
Our platform integrates with a bank’s existing anti-money-laundering (AML), customer due-diligence (CDD) and transaction-monitoring systems. It also provides out-of-the-box integration with Security Information and Event Management (SIEM) tools, alongside coarse-grained and fine-grained access controls and compliance-as-code capabilities. These features enable teams to configure and manage security policies consistently across the entire solution.
Together, these measures complement banks’ wider financial crime controls and help it respond as risk evolve. Outside of Vietnam, our existing clients benefit from our highly configurable, best-in-class security capabilities across the application and supporting infrastructure. This flexibility allows banks to adjust their security measures as threats evolve and regulatory requirements changes.
Ultimately, what matters is the bank’s ability to continually assess, deploy and demonstrate the effectiveness of those controls at speed.