If a founder in Southeast Asia downloads a SAFE template from a random website and uses it to raise a seed round in 2026, there is a real chance the document is the wrong version. Y Combinator introduced the SAFE (Simple Agreement for Future Equity) in 2013 on a pre-money basis, then quietly replaced it in 2018 with a post-money version. That change is not legal trivia. It decides who carries the dilution when a company signs more than one SAFE, and in practice, that is almost always the founder.
What actually changed
A SAFE lets an investor put money into a company now and receive shares later, usually at the next priced round. The company does not need a valuation today, which makes early rounds faster and cheaper. But a SAFE still needs a formula for how much of the company the investor will own once it converts. That is where the two versions diverge.
In the original pre-money SAFE, the investor’s ownership is calculated against the company’s value before the SAFE money, and before other SAFEs convert. The percentage the investor ends up with therefore depends on how many other SAFEs the company issues. An investor cannot compute it without seeing the full list of instruments the founder has signed, and that list is information the founder holds, not the investor.
In the post-money SAFE, the valuation cap already includes the money raised through SAFEs. The investor’s ownership is simply the investment divided by the post-money cap, and it is fixed on the day of signing. Later SAFEs do not change it.
A worked example
Take a hypothetical startup that raises US$200,000 from investor A and later US$300,000 from investor B, both at a US$4 million cap.
With post-money SAFEs, investor A owns 200,000 / 4,000,000 = 5 percent, and investor B owns 300,000 / 4,000,000 = 7.5 percent. Each percentage is locked in. Together they hold 12.5 percent, and every point of that dilution lands on the founders and any existing shareholders, before the next priced round even starts.
With pre-money SAFEs at the same cap, investor A alone would own roughly 200,000 / 4,200,000 = 4.76 percent. Once investor B arrives and both convert, the denominator grows and investor A falls to about 200,000 / 4,500,000 = 4.44 percent, while investor B gets about 6.67 percent. The two investors together hold about 11.1 percent. The investors share the effect of each new SAFE, so the founders give up less.
The gap in this example is only about 1.4 percentage points. But it grows with every additional SAFE, and it shows who bears the risk. Under the post-money version, each new instrument is a fixed claim that comes straight out of the founders’ stake.
Why the market moved to post-money anyway
Institutional investors wanted to know exactly what they own. Post-money gives them that certainty, so most funds that write seed checks now expect it, and most founders will be handed a post-money document whether they asked for one or not. In Southeast Asia, where many first-time founders raise from angels and small funds that borrow US templates, the version question often goes unexamined until the cap table is built at Series A.
That is where I see the surprise. Founders treat SAFEs as paper promises that do not appear on the cap table, so they stop adding them up. Five SAFEs signed over six months, each at a cap that felt reasonable on its own, can take a larger share of the company than a single priced round would have. The pain arrives all at once, when every SAFE converts into the Series A.
What founders should do
Keep a running table of every SAFE outstanding, with its post-money percentage, and add up the total before signing the next one. Check that the document says “Post-Money Valuation Cap” and is not an older template. Build a pro forma cap table that assumes all SAFEs convert together, because that is the only way to see what you will actually own after the next round. And judge the caps in aggregate, not one at a time: a US$4 million cap can sound generous in a single deal and be expensive across five.
The post-money SAFE is a sensible instrument. It is cleaner for investors, and it is now the standard. The founder’s job is to know the number it creates before it creates a surprise.
A longer Vietnamese-language walkthrough of the same mechanics is available at ebook.beginguru.com.
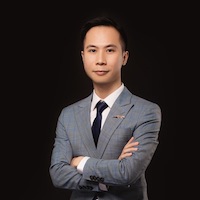
Hai H Nguyen is the founder of BeginGuru, a Forbes 30 Under 30 Asia (2017) honoree, and a fundraising coach who has served on the boards of several Vietnamese companies, including Nina Ecom Center, VCO Group, and HOPE Corp. He has spent 14 years working with founders on valuation, fundraising, and governance.
Editor’s note: This contributed article has been lightly edited for clarity and TNGlobal house style. The views expressed are those of the author.
Share your perspective: TNGlobal welcomes contributed insights and expert commentary from across Asia’s technology and innovation ecosystem. Submit a contribution for editorial consideration, or explore more in TNGlobal INSIDER and TNGlobal Q&A and Interviews.
In Southeast Asia, corporate credibility increasingly starts with the data