Editor’s notes: graphics, data & information provided by data platform Tracxn
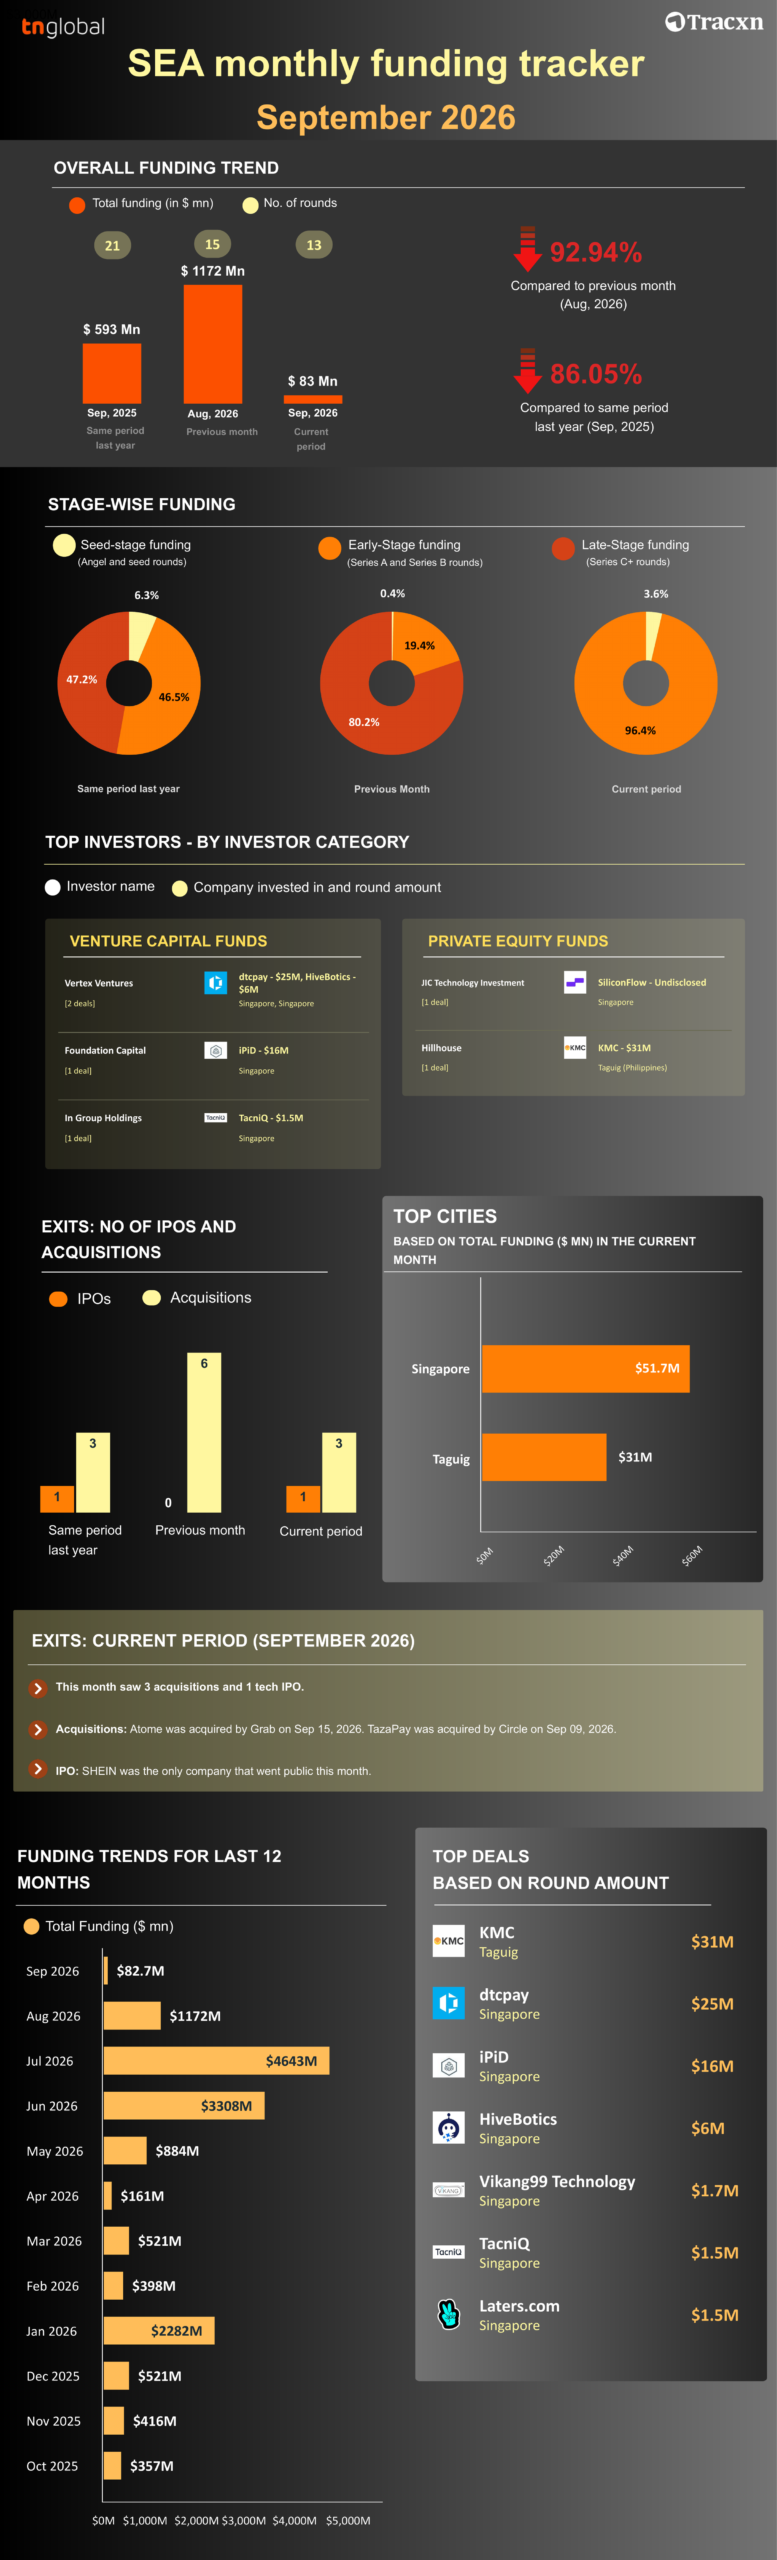
The SEA Monthly Funding Tracker for September 2026 recorded a sharp pullback in total capital deployment, reaching $82.7 million across 13 rounds. This represents a 92.94 percent decrease month-on-month (August 2026: $1,171.72 million), and an 86.05 percent decrease compared to the same period last year (September 2025: $592.72 million).
Round count also softened (13 in September 2026 versus 15 in August 2026 and 21 in September 2025), with the steep drop in dollar value. It was driven by the absence of the billion- and hundred-million-dollar late-stage rounds that had powered the preceding months, leaving September to rely on a thin set of early- and seed-stage deals.
Stage-Wise Funding Trends
September saw capital concentrate almost entirely in younger companies. Early-stage funding dominated the month, accounting for 96.4 percent ($79.7 million) of the total capital. Seed-stage rounds contributed 3.6 percent ($3 million).
Late-stage funding recorded no activity at 0 percent ($0 million). Late-stage consists of Series C onwards and PE funding.
IPOs and Acquisitions
Exit activity held broadly steady against the funding slowdown.
IPOs: 1 (compared to 0 in August 2026)
Acquisitions: 3 (compared to 6 in August 2026, and 3 in September 2025)
This month saw 3 acquisitions and 1 tech IPO. Atome was acquired by Grab on September 15, 2026. TazaPay was acquired by Circle on September 9, 2026.
SHEIN was the only company that went public (IPO) this month.
Top Funding Deals in September 2026
The month was headlined by KMC, which alone accounted for roughly 37 percent of the month’s total funding. Together, KMC and dtcpay made up about 68 percent of all capital raised.
KMC – $31 million
dtcpay – $25 million
iPiD – $16 million
HiveBotics – $6 million
Vikang99 Technology – $1.7 million
TacniQ – $1.5 million
Laters.com – $1.5 million
SiliconFlow – Undisclosed
DANA – Undisclosed
Braendz – Undisclosed
Locality Trends
Singapore remained the primary engine of SEA’s startup ecosystem, capturing the bulk of the month’s disclosed capital.
Singapore: $51.7 million
Taguig (the Philippines): $31 million
Venture Capital Funds (VC)
Vertex Ventures invested in dtcpay with $25 million, HiveBotics with $6 million (Singapore)
Foundation Capital invested in iPiD with $16 million (Singapore)
In Group Holdings invested in TacniQ with $1.5 million (Singapore)
Private Equity Funds (PE)
Hillhouse invested in KMC with $31 million (Taguig, Philippines)
JIC Technology Investment invested in SiliconFlow with an undisclosed amount (Singapore)
Key Takeaways
Sharp Correction: Total funding fell more than 14-fold versus August. At $82.7 million, September ranks among the leanest months of the trailing year.
Early-Stage Carries the Month: With no late-stage or PE dollars recorded, early-stage rounds made up 96.4 percent of all capital — an unusual inversion of the late-stage dominance seen in prior months.
Singapore’s Continued Lead: Singapore-based startups accounted for the majority of disclosed value, with Taguig’s KMC round the sole large deal outside the city-state.
Thin, Smaller Deals: Beyond KMC and dtcpay, deal sizes clustered in the low single-digit millions, including HiveBotics, Vikang99 Technology, TacniQ, and Laters.com. This reflects a month weighted toward smaller, earlier bets rather than headline raises.
Strong Exit Activity: Despite the funding slowdown, Southeast Asia recorded 3 acquisitions and 1 IPO, including the acquisitions of Atome by Grab and TazaPay by Circle, alongside SHEIN’s public listing.
Southeast Asia tech funding jumps 176% to $13.5B, 3 deals drive growth: Tracxn